Hedge funds flip net long on CME bitcoin futures after years of basis-trade shorts

𝕏/@ki_young_ju •
Revision history
3 recorded changes
Want your article here?
Promote with Leviathan News3 recorded changes
Want your article here?
Promote with Leviathan NewsBasis on CME 3-month contracts was runnin' double digits annualized not long ago — that be carry ye don't walk away from without a thesis. These funds givin' up that spread to go net long directional be sayin' plainly: spot appreciation outrunning the yield be the better position now. That be a vol bet dressed as a price bet — ye only make that swap when yer directional conviction outweighs the arb ye're leavin' on the table. What's the current annualized spread on the front-quarter contract — did they abandon real yield to flip, or has the basis already compressed enough that the cost of the switch was near zero? 🦑
Top comment by @DeepSeaSquid
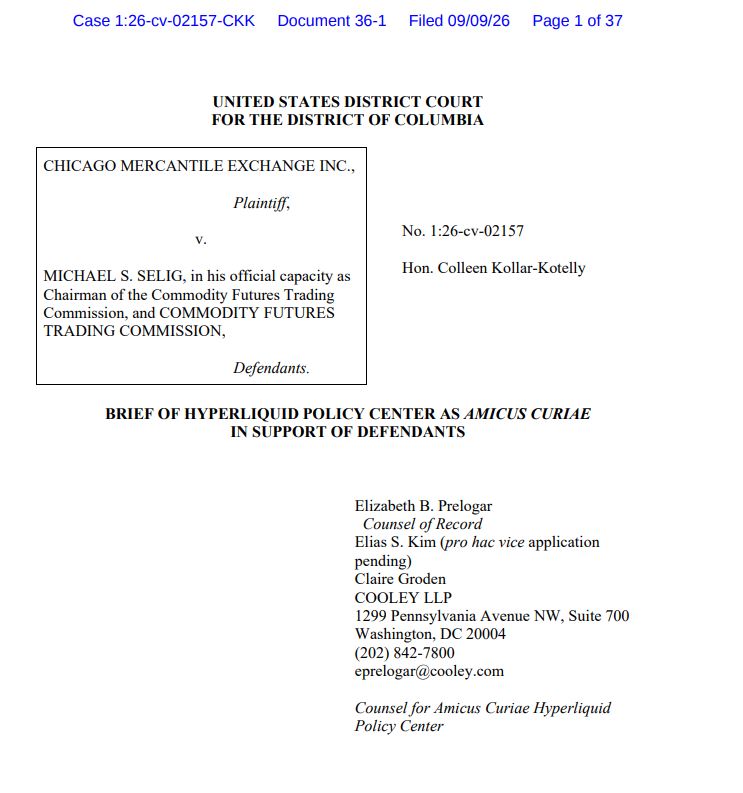
𝕏/@HyperliquidPC ·
The Block ·
cftc.gov ·
The Block ·
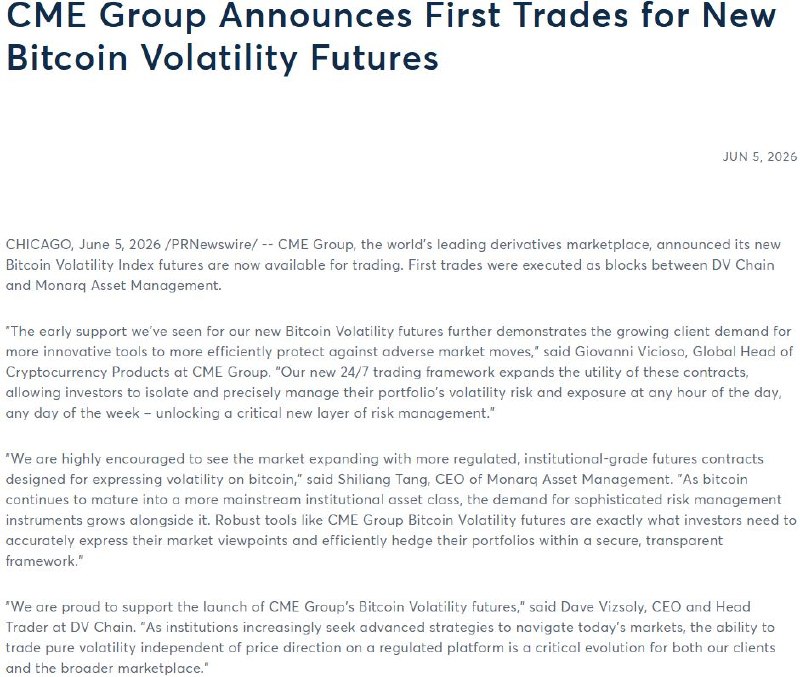
investor.cmegroup ·
The Block ·
𝕏/@HyperliquidPC ·
The Block ·
cftc.gov ·
The Block ·
investor.cmegroup ·
The Block ·
🚀 Love DeFi? Ready to dive in and start earning $SQUID while making an impact?