
Bitfinex is more than a trading venue: it is a central node in the Tether ecosystem, a case study in exchange risk, and the architect of tokenized claims whose value still depends on the aftermath of the 2016 hack.
+5 sources across the wider coverage universe
 U.S. government moves $606K in 2016 Bitfinex hack bitcoin to Coinbase; exchange to redeem all RRTs and burn LEO2026-04
 USDC is pulling ahead of USDT as stablecoin trading volume hits record highs in 2026.2026-07
 Tether’s $20 million bet on Argentina’s Ualá opens door for future crypto expansion despite current USDT limits2026-07
 Tether's USDT faces a two-year compliance countdown as the GENIUS Act moves toward full enforcement in July 2028, putting its U.S. exchange presence under pressure2026-07
 Bitfinex-backed Layer 1, Stable, unveiled its 100B-supply STABLE token, built for governance and network security while all transactions still run on USDT. A stricter phase-2 deposit campaign followed backlash over alleged insider front-running in phase 1.2025-12
 Wormhole introduces native USDT transfers for 7 networks.2024-07
Among the longest-running centralized cryptocurrency exchanges, Bitfinex occupies an unusual place in digital-asset history. It is simultaneously a trading venue for Bitcoin and stablecoins, a close corporate relative of Tether, and the site of one of the industry’s most consequential hacks. Those roles cannot be evaluated separately. Liquidity on the exchange depends heavily on USDT, the exchange’s regulatory history overlaps with questions about Tether’s reserves, and the response to the 2016 theft created a family of tokens whose economics remain tied to restitution.
That makes Bitfinex less useful as a simple exchange review than as a study of how centralized crypto infrastructure evolves under pressure. The exchange survived a catastrophic security failure, recapitalized through tokenized claims, settled major regulatory cases, and retained a role in professional trading. The benefit of that resilience is a venue with unusually deep institutional memory and a specialized product set. The cost is structural complexity: users must assess not only trading and custody risk, but also corporate concentration, stablecoin exposure, legal history, and the incentives embedded in Bitfinex-linked tokens.
Origins, Corporate Structure, and Strategic Position
Bitfinex emerged in the early 2010s, when cryptocurrency exchanges were still improvising the basic machinery of spot markets, leverage, custody, and dollar settlement. It initially appealed to professional and semi-professional Bitcoin traders who needed deeper liquidity and more sophisticated order types than early retail platforms could provide. Over time, it developed into a full-service centralized exchange under the iFinex corporate umbrella, serving active individuals and institutional counterparties through spot, margin, derivatives, funding, and over-the-counter products.
Longevity matters, but it should not be confused with simplicity or regulatory equivalence. Bitfinex has operated through multiple Bitcoin cycles and periods of severe market stress, yet its legal posture and customer protections differ from those of an onshore bank or publicly listed brokerage. The platform is best classified as offshore market infrastructure: it provides execution, leverage, collateral movement, and settlement to a global crypto clientele without fitting neatly into the regulatory model applied to a conventional securities exchange.
The corporate relationship with Tether is central to that classification. Bitfinex and the entities behind USDT have shared ownership and management links, and regulators have addressed them as parts of a connected corporate ecosystem. The relationship gives Bitfinex privileged proximity to the most widely used dollar-pegged trading asset in crypto. It also means that questions about Tether’s reserve practices, banking access, disclosures, or legal exposure can become relevant to an exchange user even when that user is interested only in executing a Bitcoin trade.
The New York Attorney General’s 2021 settlement treated Bitfinex and Tether as closely related entities whose shared management and internal transfers complicated the distinction between exchange liquidity, customer funds, and stablecoin reserves. The Commodity Futures Trading Commission likewise addressed Tether entities and Bitfinex entities in parallel enforcement actions involving reserve representations and financed retail commodity transactions. Those actions establish a history of regulatory findings about particular conduct and periods. They do not establish that every present-day Bitfinex balance is impaired or that every USDT transaction carries the same risk.
Geographically, Bitfinex has generally operated from offshore jurisdictions rather than building its identity around direct access to the United States or European Union. That approach enabled broad asset support and service to an international user base, but it also exposed the company to extraterritorial enforcement whenever regulators concluded that protected customers or regulated transactions fell within their jurisdiction. Bitfinex consequently restricted access for U.S. and New York customers while continuing to serve other markets.
This produces a hybrid position. Bitfinex can be economically important to Bitcoin and stablecoin liquidity without being legally interchangeable with a U.S.-regulated exchange. For a trader, that distinction affects onboarding, recourse, permitted products, reporting obligations, and the assumptions that can safely be made about customer-asset protection. Deep liquidity is a market property; it is not a substitute for legal protection.
Strategically, Bitfinex now spans several layers. It remains a centralized venue for spot, margin, derivatives, and block trading. It is also a primary market for tokens associated with iFinex and Tether, including UNUS SED LEO, Recovery Right Tokens, and Tether Gold. The result is not merely an exchange with affiliated products. It is the commercial center of a Tether-oriented network in which trading, token issuance, corporate financing, and infrastructure development reinforce one another.
That integration is a double-edged sword. It can concentrate liquidity and make related products easier to trade, hedge, and settle. It also concentrates dependency on a small corporate group. A disruption affecting banking access, reserves, governance, or regulation can travel across more than one product surface at once.
Tether and Fasanara launch $400M StableFund for USDT-enabled private credit, targeting SME and consumer lending across 60+ countries with plans to raise $3B more
Core Trading Platform, Products, and Market Role
At its core, Bitfinex is a centralized order-book exchange supporting spot markets, margin trading, derivatives, securities-oriented offerings, and over-the-counter execution. Its major markets have historically included Bitcoin, ether, fiat currencies, and stablecoins, with USDT occupying an unusually prominent role as a quote asset, settlement instrument, and source of collateral.
The platform is designed for traders who care about execution control. Order books, advanced order types, margin funding, and API access make it more comparable to a professional trading venue than to a simple retail purchase app. That sophistication expands what a trader can do, but it also expands the number of ways a trader can fail. Leverage turns ordinary volatility into liquidation risk, collateral choices create cross-asset exposure, and automated strategies introduce operational risk around credentials and execution logic.
Margin trading lets users borrow assets to enlarge long or short positions. Economically, the mechanism separates capital ownership from market exposure: a trader can obtain price exposure without funding the entire position, while lenders earn compensation for supplying assets. The gain is capital efficiency. The cost is that adverse price moves can force liquidation before a thesis has time to recover.
Bitfinex’s perpetual derivatives serve a similar purpose at greater abstraction. A perpetual contract tracks an underlying market without requiring the holder to own the asset or accept a fixed expiry date. Funding payments encourage the contract price to remain aligned with spot. This makes perpetuals useful for directional speculation and hedging, but the instrument adds leverage, funding-rate uncertainty, and counterparty exposure to the ordinary risk of the underlying asset.
Those markets matter beyond Bitfinex’s own customer base because leveraged venues participate in global price discovery. When large traders build positions, hedge inventory, or respond to funding differences, arbitrageurs transmit those signals between spot and derivative markets. Bitfinex is not solely responsible for a global Bitcoin price, but its liquidity can contribute to the network of venues through which that price is formed.
The exchange has also promoted a zero-fee model across major product categories. Removing explicit maker and taker fees changes the immediate economics of frequent trading: a strategy with a thin expected edge can survive more turnover when each fill does not incur a conventional percentage fee. The benefit is obvious for active traders. The trade-off is that users must understand how the venue earns money elsewhere and whether displayed volume reflects durable liquidity, fee-driven incentives, or trading behavior that would look different under a conventional schedule.
A fee-free order book can encourage tighter quoting because market makers need not recover the same explicit charge on each transaction. It can also encourage high turnover that says little about the amount of long-term capital committed to the venue. Volume is therefore best treated as one observable test, not a verdict. A trader can examine spreads, depth at different distances from the midpoint, the behavior of the book during volatility, withdrawal performance, and the cost of financing. Those measures reveal more about practical execution than a headline volume ranking alone.
Bitfinex’s over-the-counter desk addresses another part of the market. Large holders may prefer negotiated block execution when placing an order openly would move the price or reveal intent. An OTC desk can coordinate a buyer and seller, reduce visible market impact, and provide tailored settlement. The benefit is discretion and execution certainty; the cost is reduced pre-trade transparency and dependence on the intermediary’s controls.
OTC activity and public order books are not isolated. A dealer that executes a block may hedge on the exchange, and a client may transfer assets before or after settlement. Consequently, large deposits or withdrawals can reflect market making, collateral management, customer settlement, or directional positioning. On-chain movement into Bitfinex is evidence that assets moved to an address associated with the venue. It does not, by itself, prove that the assets were sold.
This distinction matters because crypto market commentary often converts transfers into narratives too quickly. The useful test is whether the transfer is followed by identifiable exchange activity, a corresponding change in open interest, a shift in order-book liquidity, or a disclosed corporate transaction. Without that second step, the movement establishes positioning capacity, not trading intent.
Readers click Bitfinex stories for two irreconcilable realities: the exchange's CTO publicly denying a confirmed 2.5-TB breach while Bitfinex Securities simultaneously pitches tokenized bonds — signaling readers track the gap between Bitfinex's institutional ambitions and its unresolved trust deficit.
Bitfinex, Tether, and the Stablecoin Landscape
Understanding Bitfinex requires understanding why stablecoins became essential to crypto market structure. A dollar-pegged token lets traders move a dollar-like unit between exchanges and blockchains without relying on a bank transfer for every transaction. It can serve as a quote currency, collateral asset, treasury balance, remittance rail, and bridge between decentralized and centralized markets.
USDT became the dominant expression of that model. Its usefulness comes from network effects: exchanges list it, traders quote against it, market makers hold it, and users in markets with limited dollar access can transfer it around the clock. The same network effects create concentration risk. When a stablecoin becomes the common settlement layer across otherwise separate venues, doubts about its liquidity or redeemability can propagate widely.
Tether historically marketed USDT as backed by reserves and redeemable against fiat value. The CFTC’s 2021 order found that, during the period it examined, Tether made misleading statements about the nature and sufficiency of those reserves. The order said the reserves were not fully held in fiat currency at all relevant times and sometimes included other assets and receivables. That finding establishes that earlier public descriptions overstated the composition and consistency of backing during the specified period. It does not mean that every reserve asset was fictitious or that every subsequent disclosure can be inferred from the earlier conduct.
Bitfinex’s role arose from more than simply listing USDT. The exchange relied on the token as a major trading rail while sharing corporate ties with its issuer. The New York Attorney General alleged that roughly $850 million in Bitfinex customer and corporate funds became inaccessible after being placed with a payment processor and that Bitfinex then drew on Tether reserves to address the shortfall. Under the 2021 settlement, Bitfinex and Tether agreed to pay $18.5 million, end trading relationships with New York residents and entities, and provide reserve-related reporting, without admitting or denying the findings.
That episode is best understood as a problem of corporate boundaries. A stablecoin reserve is supposed to support token liabilities, while an exchange balance sheet supports the exchange’s own obligations. When money can move between related entities, users need clarity about which pool bears which risk. Corporate affiliation can make emergency liquidity easier to coordinate; it can also weaken the separation that allows creditors to understand their position.
Bitfinex supports assets beyond USDT, including other dollar-pegged tokens. That reflects a commercial necessity. Even an exchange closely aligned with one issuer benefits from letting customers move among different forms of dollar exposure. Stablecoins differ in issuer, reserve composition, banking relationships, supported chains, redemption access, and regulatory posture. A one-dollar market price during normal conditions does not erase those distinctions.
The comparison between USDT and USDC is therefore not simply a contest over which token is more transparent or more popular. It is a choice among settlement networks. USDT’s broad offshore and cross-border adoption can make it easier to use across many venues. USDC’s institutional and regulated-market positioning can make it preferable for counterparties with different compliance requirements. Supporting both allows an exchange to serve users whose constraints are legal and operational, not merely speculative.
Stablecoins also blur the boundary between cash and financial product. A token can look like idle dollars to one holder, trading collateral to another, and deployable lending capital to a third. Once it is deposited into a protocol or pledged against leverage, the risk no longer stops with the issuer. Smart contracts, liquidators, collateral markets, governance, bridges, and oracles can all sit between the holder and eventual repayment.
This reclassifies USDT from an exchange convenience into general-purpose financial infrastructure. The gain is composability: the same unit can move through trading, payments, lending, and settlement. The cost is risk stacking. A user may simultaneously depend on Tether, a blockchain, a wallet, a bridge, a lending protocol, and a front-end provider while experiencing the result as a single dollar balance.
For Bitfinex, USDT’s reach provides liquidity and commercial gravity. It also ensures that developments far beyond the exchange can affect its markets. Demand for stablecoin borrowing, changes in redemption behavior, disruptions on supported networks, or regulatory restrictions can influence deposits, withdrawals, spreads, and collateral preferences even when Bitfinex’s matching engine is operating normally.
The 2016 Bitfinex Hack: Anatomy and Legal Aftermath
Any durable assessment of Bitfinex has to begin with the breach of August 2, 2016. Attackers stole 119,755 BTC from the exchange, worth roughly $70 million to $72 million at the time. Later U.S. government descriptions commonly rounded the amount to approximately 120,000 BTC. Bitcoin’s subsequent appreciation transformed the theft from a major exchange loss into a multibillion-dollar legal and financial problem.
The custody design involved a multisignature arrangement associated with BitGo. Multisignature systems are intended to prevent one compromised key from authorizing a transfer, but their security depends on the entire approval workflow. If attackers can manipulate account logic, credentials, transaction construction, or an automated co-signing process, multiple nominal keys may not provide genuinely independent controls.
The hack therefore belongs in the category of systems failure, not simply key theft. Cryptographic architecture mattered, but so did the surrounding operational design. A secure primitive can be embedded in an insecure process. That lesson remains relevant to exchanges, custodians, bridges, and smart-contract wallets: the number of signatures is less important than whether each signer performs an independent and meaningful check.
Bitfinex responded with a generalized loss allocation rather than placing the entire shortfall on the accounts directly associated with the stolen wallets. Customers received BFX tokens corresponding to the dollar value of the imposed loss. The token represented a claim that could be redeemed or converted into equity, turning an immediate balance-sheet hole into a time-dependent obligation.
The structure resembled emergency recapitalization more than ordinary customer reimbursement. It gave Bitfinex time to rebuild capital and continue operating, while users temporarily bore credit and liquidity risk. The benefit was continuity and a route to nominal recovery. The cost was that customers received an instrument created by the same company whose custody system had failed, without the protection of deposit insurance or a conventional resolution regime.
Bitfinex later reported that all outstanding BFX tokens were redeemed at par or exchanged for iFinex shares within eight months. That establishes that the tokenized claims were resolved in nominal dollar terms through redemption or conversion. It does not mean every customer experienced the same economic result, because timing, liquidity needs, token-sale decisions, and the opportunity cost of lost Bitcoin exposure could differ materially.
Once the BFX stage ended, Recovery Right Tokens became the mechanism for allocating proceeds from any future recovery. RRTs grant holders a claim on qualifying recovered funds, subject to the token terms and capped at one dollar per token. The sequence matters: the BFX obligations came first, RRT holders occupy a defined recovery position, and other corporate uses of residual proceeds follow the contractual structure described by Bitfinex.
RRTs are best understood as tokenized contingent claims. Their value depends less on Bitfinex’s daily trading revenue than on legal recovery, asset disposition, timing, expenses, and the company’s performance of the stated redemption process. They resemble a narrow form of litigation finance: holders accept uncertainty about courts and law enforcement in exchange for exposure to a defined recovery waterfall.
The investigation took years. The U.S. Department of Justice said Ilya Lichtenstein hacked Bitfinex and then used a complex laundering scheme involving layered transfers, mixers, exchanges, darknet markets, and bank accounts. Heather Morgan assisted with laundering portions of the proceeds, according to the government’s case. U.S. authorities arrested the pair in February 2022 and announced the seizure of more than 94,000 BTC associated with the theft.
Lichtenstein pleaded guilty in August 2023 to money-laundering conspiracy, and Morgan also entered a guilty plea. Those proceedings changed the central uncertainty. Before the seizure, the main question was whether the coins could be located and controlled. Afterward, the main questions became legal ownership, forfeiture, victim status, restitution mechanics, and the treatment of an asset worth far more than at the time of the offense.
Bitfinex has also described smaller recoveries achieved with law-enforcement assistance before the major seizure, including 27.66 BTC in 2019 and 6.51 BTC in 2021. Those amounts were tiny beside the original loss, but they demonstrated that traced cryptocurrency can remain recoverable years after a theft. Public blockchains preserve transaction history; they do not guarantee recovery, but they can make stolen funds persistently observable when criminals attempt to move them.
The scale of the later seizure introduced a difficult question: who is the victim when customers were already compensated through a mixture of token redemption and equity conversion? Bitfinex can argue that it assumed the economic loss and resolved customer claims, while former customers or other claimants may focus on the difference between nominal dollar compensation and the appreciated value of the stolen Bitcoin. That is a legal allocation problem, not something the blockchain itself can answer.
The distinction between seized and forfeited assets also matters. Seizure places property under government control while legal proceedings continue. Forfeiture establishes the government’s legal ownership or authority to dispose of it. Restitution may direct value to victims under a separate framework. Treating all government-controlled Bitcoin as freely saleable ignores those procedural stages.
For the market, the relevant test is not simply whether a government address moves. Traders need to know the legal purpose, recipient, restrictions, and expected disposition. A transfer made to implement restitution has different implications from an auction, an internal custody change, or a sale. On-chain visibility identifies movement; court records and official statements establish why it occurred.
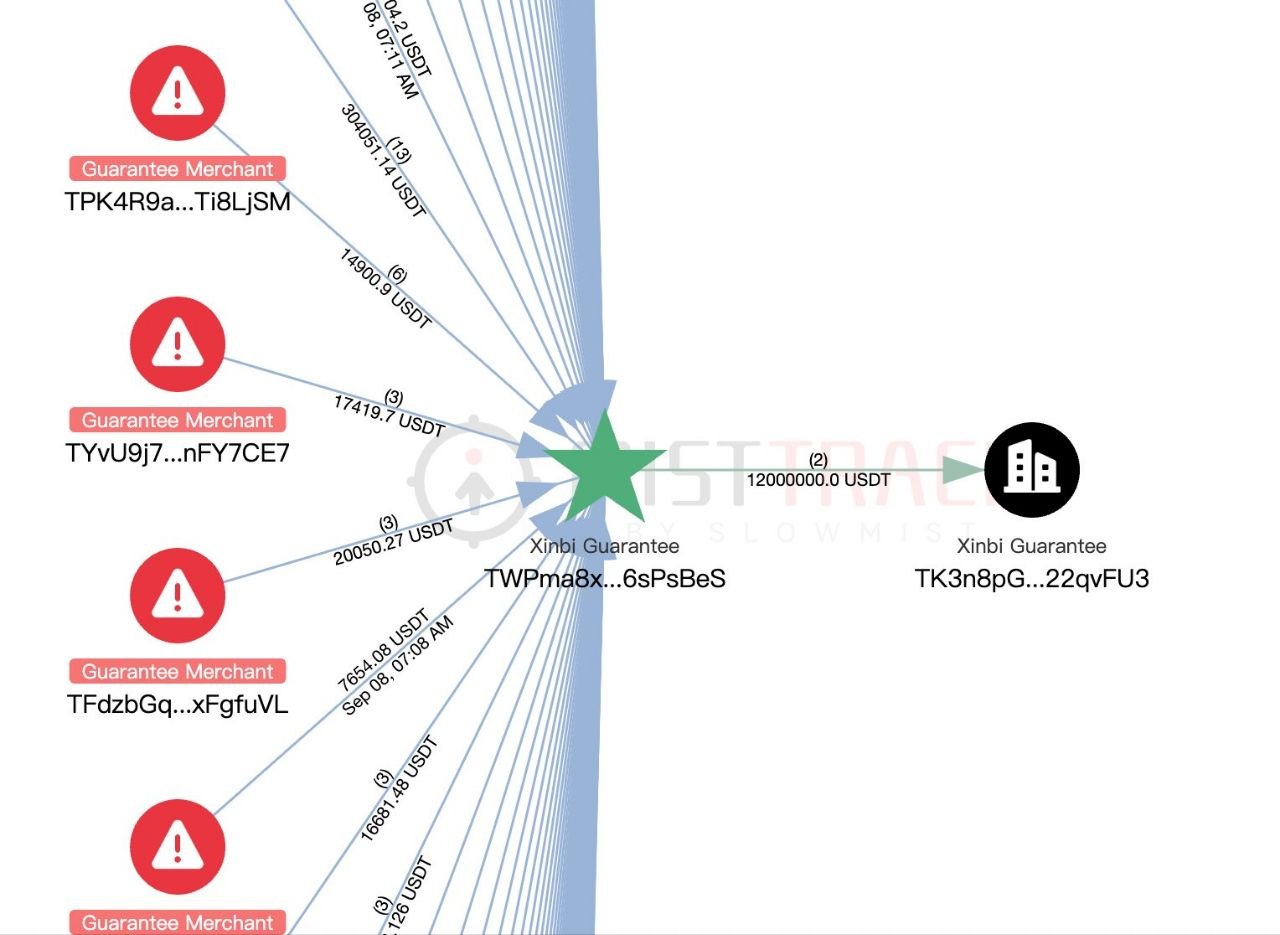
Tether freezes $39.3M in USDT across 10 Tron addresses linked to Xinbi Guarantee, an illicit crypto marketplace reportedly processing $24.2B in transactions
BFX, RRT, UNUS SED LEO, and XAUT
The 2016 crisis produced an unusual sequence of tokenized financial instruments. BFX distributed the immediate loss across time. RRT assigned rights to future recoveries. UNUS SED LEO later connected iFinex revenue and certain windfalls to a buyback-and-burn mechanism. Tether Gold extended the wider corporate ecosystem into tokenized commodities. Together, these instruments show how Bitfinex has used tokens not merely as assets to list, but as tools for recapitalization, claims management, corporate incentives, and product expansion.
BFX was temporary by design. Holders could seek redemption or convert their claims into iFinex equity, and the tokens ceased to matter once the obligations were resolved. Its historical importance lies in the precedent: an exchange facing a balance-sheet crisis imposed a generalized loss and issued a transferable instrument instead of entering a familiar bank-style resolution process.
The approach worked in the narrow sense that Bitfinex continued operating and reported full nominal resolution of BFX claims. It should not be generalized into a guarantee that tokenized recapitalization will work elsewhere. The outcome depended on the exchange’s ability to retain customers, generate value, maintain trading, and honor the claims. A token can document an obligation; it cannot create the cash flow needed to satisfy it.
RRT occupies a different position because it remains tied to uncertain recoveries. Each token’s maximum payout is constrained, so its economic value does not rise proportionally with Bitcoin once expected proceeds are sufficient to cover the outstanding claim. Its price should instead reflect the probability and timing of redemption, legal and administrative costs, the number of eligible tokens, and confidence in execution.
This makes RRT a useful example of how token prices can encode legal expectations. A discount to the maximum redemption value may indicate delay, uncertainty, illiquidity, or counterparty risk. A move toward par may indicate increased confidence that enough qualifying funds will reach the relevant part of the waterfall. Neither price proves what a court will decide.
UNUS SED LEO is broader. Introduced as an iFinex utility token, it provides platform-related benefits and participates in a company-funded buyback and burn program. Its investment case depends on iFinex activity and on the expectation that specified revenues or recoveries will be used to remove tokens from circulation.
The documentation associated with LEO states that up to 80% of net funds recovered from the 2016 hack will be used for repurchases and burns within 18 months of receipt. Repurchases may occur through open-market or over-the-counter transactions. That mechanism gives LEO holders indirect exposure to the value of a recovery, but it does not give each holder direct title to recovered Bitcoin.
The distinction is crucial. RRT is a capped claim within a stated recovery sequence. LEO is a utility token affected by corporate repurchase commitments and market expectations. Equity in iFinex is a separate ownership interest. Treating the three as interchangeable obscures who has a contractual claim, who benefits indirectly, and who bears residual corporate risk.
LEO therefore acts partly as a proxy for confidence in Bitfinex. Strong exchange activity can support the buyback thesis, while major recoveries could accelerate burns. The benefit is alignment between token scarcity and corporate performance. The cost is dependence on a private corporate group’s revenues, disclosures, implementation choices, and legal outcomes.
Tether Gold, or XAUT, sits outside the hack waterfall. It represents exposure to physical gold through a blockchain token and is traded on Bitfinex. Its strategic importance is that it extends the exchange’s settlement environment beyond crypto-native assets and dollar stablecoins. A trader can move among Bitcoin, ether, dollar-pegged tokens, and tokenized gold without leaving the same market infrastructure.
That convenience does not make the risks identical. Bitcoin is a bearer asset governed by its network. USDT is an issuer-backed liability. XAUT depends on claims to vaulted metal and the issuer’s redemption framework. LEO depends on iFinex-related utility and buybacks. RRT depends on recovery rights. They may trade beside one another, but each belongs to a different legal and economic category.
| Token | Economic category | Primary function | Relationship to the 2016 hack | Principal dependency |
|---|---|---|---|---|
| BFX | Recapitalization claim | Deferred or converted customer compensation | Created directly after the loss | Bitfinex’s ability to redeem or convert claims |
| RRT | Contingent recovery right | Capped participation in qualifying recoveries | Directly tied to recovered property | Legal recovery and execution of the redemption waterfall |
| UNUS SED LEO | Exchange utility token | Platform benefits and company-funded buybacks | Indirect exposure through recovery-funded burns | iFinex performance and fulfillment of buyback commitments |
| XAUT | Tokenized commodity claim | Blockchain-based gold exposure | No direct recovery role | Issuer, custody, and redemption arrangements for the metal |
The family resemblance is tokenization, not economic equivalence. Bitfinex turned several different relationships—creditor, recovery claimant, platform user, and commodity holder—into transferable instruments. That expands liquidity and price discovery, but it can also make contractual differences look smaller than they are.
- 01Bitfinex breach accountability↗
The confirmed 2.5-TB data leak affecting 400K customers (194 clicks) paired with the CTO's denial (141 clicks) drove readers to assess who was telling the truth and what customer exposure actually looked like.
- 02Bitfinex Securities tokenized bonds↗
The Mikro Kapital bond issuance on Liquid Network (256 clicks) pulled readers curious whether a scandal-scarred exchange could credibly operate a regulated securities arm.
- 03Tether USDT sanctions exposure↗
Headlines about $20B USDT entering sanctioned Russian exchange Garantex (203 clicks) and a $1.9B underground banking ring (308 clicks) kept readers tracking Tether's — and by extension Bitfinex's shared-ownership — regulatory liability.
- 04USDT cross-border payment expansion↗
Tether's $18.75M XREX investment (226 clicks), TON integration (323 clicks), and El Salvador citizenship program (173 clicks) showed readers USDT utility growing in corridors regulators struggle to monitor.
- 052016 hack recovery and RRT payouts↗
The multi-year saga of recovering seized BTC and returning value to RRT token holders tracks whether Bitfinex actually made victims whole, a story with unresolved chapters still drawing reader interest.
Regulatory and Legal Track Record
Bitfinex’s regulatory history reflects the recurring conflict between offshore crypto platforms and authorities applying domestic commodity, payments, or consumer-protection rules. The exchange’s location does not by itself determine whether a regulator will claim jurisdiction. Customer location, solicitation, transaction structure, custody, and the use of local financial infrastructure can all matter.
The CFTC’s 2021 order settled charges against Tether entities concerning statements about USDT reserves and against Bitfinex entities concerning financed retail commodity transactions and registration. The order concluded that Bitfinex offered certain financed transactions to U.S. persons who were not eligible contract participants and acted in capacities requiring registration as a futures commission merchant. Bitfinex agreed to a $1.5 million civil monetary penalty and cease-and-desist provisions, while Tether agreed to a $41 million penalty concerning reserve representations.
The regulatory principle is more durable than the amounts. Crypto terminology does not displace the economic substance of a transaction. If a platform extends financing, takes the other side of a leveraged commodity trade, and holds customer property in connection with that activity, regulators may classify the conduct under existing derivatives or commodities rules even when the interface calls it margin trading in digital assets.
The New York Attorney General’s settlement focused on a different set of concerns: the inaccessible funds associated with a payment processor, transfers involving Tether reserves, reserve disclosures, and service to New York customers. The settlement imposed an $18.5 million payment, reporting requirements, and a prohibition on trading with New York residents and entities.
These cases establish that Bitfinex and Tether have faced material findings and restrictions from U.S. authorities. They do not make Bitfinex illegal everywhere, nor do they convert a settlement into continuous supervision equivalent to that applied to an onshore bank. The practical conclusion is narrower: users cannot evaluate the venue solely through its home jurisdiction or website eligibility rules.
A persistent claim around the 2016 hack was that regulatory intervention forced Bitfinex into a weaker custody design. Analysis from Coin Center disputed that causal story, arguing that the relevant CFTC rules addressed leveraged trading for U.S. customers and did not require the specific technical arrangement that failed. The distinction is important because chronology is not causation. A compliance change may precede a security incident without mechanically producing the vulnerability exploited.
The stronger explanation is operational. Bitfinex selected and implemented a custody workflow whose protections did not prevent the unauthorized withdrawals. Regulatory constraints may influence architecture, but security responsibility still rests with the entities designing, approving, and operating the system.
The broader lesson for institutional users is that compliance and solvency analysis must sit beside technical analysis. An exchange can have a secure matching engine and still face payment-processor risk. It can maintain reserves and still expose customers to jurisdictional restrictions. It can survive enforcement and still offer fewer legal remedies than a domestic regulated venue.
Due diligence should therefore ask several separate questions. Which legal entity contracts with the customer? Where are disputes heard? Which products are available in the customer’s jurisdiction? How are customer assets held? What disclosures exist for affiliated entities? What happens if a payment partner fails or a regulator freezes access? Combining those questions into a single label such as regulated or offshore hides the actual risk.
Security, Custody, and Risk Management
The central security lesson of the Bitfinex hack is that custody must be evaluated as a process. Cold storage, multisignature approval, hardware devices, withdrawal limits, and monitoring tools are controls, but they work only if they create independent barriers. If the same compromised system can instruct multiple components, apparent redundancy may be cosmetic.
A robust design separates duties and failure domains. One person or service should not be able to initiate, approve, and conceal a withdrawal. Large transfers should trigger controls distinct from normal customer activity. Backup keys should not be accessible through the same infrastructure as active keys. Monitoring should detect not only unusual transaction size, but also coordinated withdrawals spread across many accounts.
Bitfinex has described stronger security practices and cooperation with law enforcement in the years since the breach. The absence of another publicly known theft on the same scale is relevant operational evidence, but it is not proof that custody is risk-free. Security can be tested only imperfectly from outside, and centralized exchanges necessarily retain some hot-wallet or transaction-signing exposure to process withdrawals.
For users, the appropriate response is role separation. An exchange is optimized for trading and settlement, while self-custody or specialist custody is optimized for long-term asset control. Keeping every asset off an exchange can make active trading cumbersome; keeping long-term reserves on an exchange concentrates counterparty risk. The sensible balance depends on activity, technical ability, legal needs, and the cost of moving collateral.
Institutions often address the trade-off with qualified custodians, multiparty computation, whitelisted settlement networks, and limits on exchange balances. These tools reduce exposure duration but add integration complexity and additional counterparties. There is no custody arrangement without trust or operational assumptions; the goal is to make those assumptions explicit and prevent one failure from controlling the entire balance.
Stablecoins add another custody layer. Holding USDT on Bitfinex creates exposure to both the exchange and the token issuer. Deploying that USDT into a lending protocol adds smart-contract, collateral, oracle, liquidation, and governance risk. Bridging it to another network adds bridge risk. A quoted yield should therefore be compared with the complete loss path, not merely with the return on an idle dollar balance.
The same reasoning applies to leverage. A position may be economically hedged against Bitcoin price movement while remaining exposed to funding costs, exchange solvency, collateral depegging, liquidation mechanics, or withdrawal interruptions. Risk management is not only predicting price. It is identifying which dependency can force an unwanted outcome even when the market thesis is correct.
Bybit launches USDT-settled FX perpetual contracts for EUR/USD, GBP/USD, USD/JPY
Bitcoin Liquidity and Market Structure
Bitfinex remains important because Bitcoin markets need more than retail access. Professional participants require deep books, financing, short exposure, derivatives, block execution, and reliable movement between fiat-like collateral and cryptoassets. Bitfinex combines those functions in an environment where USDT is deeply integrated.
Spot markets provide direct ownership transfer. Margin markets let traders borrow assets and express leveraged views. Perpetuals create synthetic exposure and hedging capacity. OTC execution moves large blocks with less visible impact. These are different products, but arbitrage links their prices. A dislocation in one market can attract traders who buy in one place and sell in another until the gap narrows.
That networked price formation explains why an exchange can matter even when it is not the largest by aggregate volume. The relevant question is whether its marginal liquidity is useful during stress. A venue with ordinary volume but resilient depth can contribute more to price discovery than one whose activity disappears when volatility rises.
Zero explicit fees may strengthen Bitfinex’s appeal to high-frequency and market-making strategies. Yet fee policy alone cannot guarantee good execution. Traders should compare the spread, available size, realized slippage, rejection rate, financing expense, liquidation rules, and withdrawal reliability. The cheapest posted fee can coexist with a costly overall trade.
USDT further shapes the exchange’s Bitcoin markets. A BTC/USDT pair embeds two prices: the market’s value for Bitcoin and its value for the stablecoin relative to dollars. When USDT trades away from its peg, a change in the pair may not represent a matching change in Bitcoin’s fiat value. Professional traders therefore compare BTC/USDT with fiat and other stablecoin pairs before treating the move as a clean Bitcoin signal.
This is one reason stablecoin health matters to exchange liquidity. If market makers become uncertain about redemption or banking access, they may widen spreads, reduce size, demand a premium, or shift collateral. The matching engine may remain online while market quality deteriorates. Operational uptime and economic liquidity are not the same thing.
The hack-related Bitcoin adds a separate source of market attention. Large recovered balances under government or court control can generate speculation about sales, restitution, or transfers. The size of a wallet makes the question consequential, but it does not answer it. Market impact depends on whether coins are sold, returned in kind, distributed gradually, retained, or used to satisfy claims through another mechanism.
The observable test is a chain of evidence: a legally authorized disposition, an identifiable transfer, a recipient, and subsequent market behavior. Removing any link invites overstatement. A court filing without execution is not a sale; an address movement without legal context is not a liquidation; a deposit to an exchange is not proof of a completed trade.
119,756 BTC stolen in multisig exploit
RRT tokens issued to socialize losses
NY AG $18.5M settlement over Tether reserve misrepresentation
CFTC fines Tether $41M and Bitfinex $1.5M
DOJ seizes 94,000 BTC linked to 2016 hack; arrests Lichtenstein and Morgan
Bitfinex begins returning seized BTC proceeds to RRT holders
Bitfinex Securities tokenizes Mikro Kapital bond on Liquid Network
Bitfinex confirms 2.5-TB data breach affecting 400K customers
Stablecoin-Native Infrastructure and the Tether Orbit
Bitfinex’s strategic importance increasingly comes from the infrastructure surrounding the exchange rather than the order book alone. Tether-linked products have expanded the group’s relevance across settlement, tokenized commodities, payments, and blockchain ecosystems. The common thesis is that stablecoins can become the primary transactional layer of crypto rather than a temporary parking place between speculative trades.
That is a meaningful reclassification. A conventional blockchain centers its volatile native token as the unit used for fees, security, and economic coordination. A stablecoin-first system tries to make dollar-denominated value the default experience for users and businesses. The gain is predictable accounting and easier translation into commercial terms. The cost is deeper dependence on an issuer, its reserves, and the jurisdictions capable of influencing it.
Bitfinex benefits when USDT circulates across more networks because each new venue can create demand for issuance, redemption, hedging, market making, and centralized settlement. It can list associated assets, support deposits and withdrawals, and connect fragmented pools of liquidity. The exchange becomes a bridge between centralized and decentralized finance.
But bridges transmit risk in both directions. A failure in a decentralized protocol can produce liquidations and stablecoin demand on centralized markets. A disruption at a centralized issuer can impair collateral across decentralized applications. Greater integration improves capital efficiency during normal conditions while increasing the number of channels through which stress can spread.
Tokenized real-world assets extend the same model. XAUT brings gold exposure into a crypto trading environment, while securities-oriented Bitfinex businesses seek to connect conventional assets with blockchain settlement. The attraction is continuous transferability, fractional access, and interoperability with digital collateral. The hard questions concern title, custody, redemption, legal enforceability, market depth, and what happens when the token market and the underlying asset market operate on different schedules.
An apt comparison is a warehouse receipt that can circulate globally. The receipt is useful because traders do not need to move the physical commodity for every transaction. Its value nevertheless depends on the warehouse, the legal claim, and the ability to redeem. Tokenization changes the speed and programmability of the receipt; it does not eliminate the underlying custodial relationship.
This is where Bitfinex’s history is informative. The company has repeatedly used tokens to make slow or illiquid relationships tradeable: customer claims through BFX, recoveries through RRT, corporate buyback expectations through LEO, and vaulted gold through XAUT. The pattern is coherent. Bitfinex is not only an exchange for tokens; it is an institution that turns contractual and financial relationships into tokens.
The advantage is that markets can price those relationships continuously. The disadvantage is that a liquid token can create an impression of simplicity around a complicated claim. The essential test is always the same: what legal or economic right does the token confer, against whom, under what conditions, and through which redemption process?
Comparison With Other Exchange Models
Bitfinex is best compared with other exchanges along several axes rather than through a single ranking. Scale measures trading activity. Regulation measures legal status and supervision. Product breadth measures what users can do. Stablecoin relationships reveal settlement dependencies. Custody and corporate structure determine where losses may fall.
Coinbase represents a more onshore and publicly disclosed model, with a strong emphasis on U.S. compliance, institutional custody, and USDC-related infrastructure. That model can provide clearer corporate reporting and legal access for eligible U.S. customers, but it also limits products and jurisdictions according to domestic rules.
Binance historically pursued a broader international model with extensive spot and derivatives markets, many asset listings, and significant USDT liquidity. Its scale creates network effects, while its multi-jurisdictional history introduces a different set of regulatory and entity-selection questions.
Bitfinex occupies a narrower but distinctive position. It combines offshore professional trading infrastructure with unusually close integration into the Tether ecosystem and a set of proprietary financial tokens shaped by its own history. It is smaller than the largest global venues, but raw size is not its primary differentiator. Its niche lies in Bitcoin and stablecoin liquidity, advanced trading tools, affiliated products, and continuity across market cycles.
The trade-off is sharper than a feature comparison suggests. A user choosing Bitfinex may gain specialized markets, fee advantages, and access to the Tether orbit. The same user accepts a venue whose corporate relationships, prior enforcement actions, and recovery-token structure require more analysis than a straightforward brokerage account.
| Model | Primary strength | Primary trade-off | Stablecoin orientation |
|---|---|---|---|
| Bitfinex | Professional trading and integration with affiliated token markets | Offshore legal complexity and corporate concentration | Strongly centered on USDT while supporting alternatives |
| Binance | Scale, product breadth, and broad asset coverage | Complex multi-jurisdictional regulatory exposure | Extensive use of USDT and other stablecoins |
| Coinbase | Onshore access, public-company disclosure, and institutional custody | More constrained product availability under U.S. rules | Closely associated with USDC infrastructure |
No row is universally safer or more useful. A market maker, a U.S. retail buyer, an offshore fund, and a long-term holder have different requirements. The correct comparison begins with the user’s legal location, trading strategy, custody plan, collateral preference, and need for recourse.
Bitfinex and Tether settled with the NY AG for $18.5M in 2021 and Tether paid a $42.5M CFTC fine the same year; ongoing DOJ investigations into USDT flows through sanctioned entities keep legal exposure elevated.
Bitfinex and Tether share ultimate ownership through iFinex, meaning a regulatory or solvency shock to one entity structurally threatens the other and the USDT peg simultaneously.
The 2016 hack exploited Bitfinex's multi-signature wallet implementation with BitGo, draining ~119,756 BTC; the architecture has since changed but the incident established that custodial design failures can be catastrophic.
LEO tokens were issued to socialize hack losses across the user base, creating an ongoing obligation that ties exchange revenue to token buybacks and introduces reflexive price risk if volumes decline.
Bitfinex remains a top-ten exchange by volume but trails Binance and OKX significantly; thinner order books increase slippage risk for large traders and amplify volatility during stress events.
The 2024 data breach — 2.5 TB allegedly exfiltrated affecting 400K customers — was initially denied by the CTO but later confirmed, indicating persistent gaps between internal security posture and public disclosure.
What to Watch
Bitfinex’s future depends on four linked variables: the final treatment of recovered hack assets, the credibility and reach of USDT, the exchange’s ability to preserve useful liquidity, and the success of its expansion from trading venue into tokenized financial infrastructure.
The recovery process has the clearest direct consequences. RRT holders depend on the recovery waterfall and timing. LEO holders depend indirectly on the buyback and burn commitments associated with net recovered funds. Bitfinex and former customers may have competing interpretations of who absorbed the original loss and who should benefit from appreciated Bitcoin. Courts and administrators, rather than token markets, determine the legal allocation.
The most useful signals will be specific: final orders identifying recipients, transfers that implement those orders, RRT redemption activity, and disclosed LEO repurchases or burns. Price appreciation alone is not proof that any of those steps has occurred.
USDT is the second variable. Bitfinex benefits from its network effects, but those benefits bring dependence on reserve management, banking relationships, regulatory access, and confidence in redemption. The strongest evidence of durability is not market capitalization in isolation. It is the ability to process issuance and redemption, maintain liquidity across venues, preserve the peg during stress, and provide disclosures that let counterparties understand the assets and obligations involved.
Exchange liquidity is the third variable. Zero fees can attract turnover, but durable relevance requires market makers, stable financing, orderly liquidation, reliable withdrawals, and enough depth to handle volatility. Users can test these properties directly through spreads, order-book depth, funding conditions, settlement performance, and behavior during market shocks.
The final variable is whether Bitfinex can translate its history of tokenized claims into broader infrastructure without reproducing the same concentration risks. Tokenization can make commodities, securities, recoveries, and corporate incentives easier to transfer. It cannot remove the issuer, custodian, governing contract, or legal system behind them.
Bitfinex’s record supports two conclusions at once. The exchange has demonstrated unusual organizational resilience: it survived a major theft, resolved its BFX recapitalization instruments in nominal terms, continued operating through enforcement actions, and retained a professional trading niche. It has also demonstrated why resilience is not the same as low risk. Customers have repeatedly depended on private governance, affiliated companies, novel token structures, and legal processes outside ordinary deposit protection.
That tension is the durable thesis. Bitfinex is neither merely a survivor nor merely a cautionary tale. It is a piece of crypto market infrastructure built around the conversion of difficult financial relationships into tradeable instruments. If recovered assets are distributed according to clear rules, USDT remains liquid under stress, and Bitfinex preserves reliable execution, the exchange can remain an important bridge between Bitcoin, stablecoins, and tokenized finance. If any of those conditions fails, the same integration that gives Bitfinex its strategic value will transmit the weakness across its ecosystem.
Latest Bitfinex news
Tether and Fasanara launch $400M StableFund for USDT-enabled private credit, targeting SME and consumer lending across 60+ countries with plans to raise $3B moreTether freezes $39.3M in USDT across 10 Tron addresses linked to Xinbi Guarantee, an illicit crypto marketplace reportedly processing $24.2B in transactionsBybit launches USDT-settled FX perpetual contracts for EUR/USD, GBP/USD, USD/JPY Flex rolls out stablecoin wallet and payments in 170 countries, supporting USDC and USDT transfers and conversions.
 Zoomex launches 2026 multi-asset trading championship with prize pool of up to 5 million USDT
Sources
20 records from 16 domains
bitfinex.com
justice.gov
cube.exchange
cftc.gov
eco.com
coincenter.org
x.com
blog.bitfinex.com
binance.com
facebook.com
cantor.com
chainalysis.com
blog.volkovlaw.com
coinmarketcap.com
support.bitfinex.com
trading.bitfinex.com
Community notes
Spot something off or out of date? Drop a note. Editors review topic notes daily and roll accepted fixes into the explainer — contributors are recognized in the monthly $SQUID drop.
Loading notes…
Help improve this topic
Have a story or tip about this topic? Submit it. See something missing? Leave a note. Editors review daily; accepted submissions and fixes count toward the monthly $SQUID drop.