
Bybit has grown from a derivatives specialist into a broad crypto-finance platform. Its opportunity lies in joining trading, tokenization and institutional services; its central tests remain regulation, product transparency and custody security.
- x.com33
- announcements.bybit.com11
- coindesk.com8
- theblock.co7
- prnewswire.com5
- bybit.com4
- cointelegraph.com4
+18 sources across the wider coverage universe
 Mantle, Bybit, and Backed bring tokenized US equities onchain via xStocks with over $1.6B in volume2026-04
 Bybit and Bitget churn reserves 3-5x faster than Coinbase and Binance as top CEX holdings hit $225B2026-04
 Bybit says institutional crypto risk now extends beyond custody, with compliance, governance, reporting and settlement controls becoming essential infrastructure for digital assets2026-07
 Bybit intercepts coordinated fake DOT deposit scheme exploiting batch transactions, preventing over $1 billion in potential losses2026-04
 Coinbase and Bybit reportedly explore collaboration on tokenizing U.S. stocks, focusing on custody and distribution without any equity stake or market entry deal2026-04
 Bybit CEO Ben Zhou warns crypto security threats are a constant battle, reflecting on lessons from last year’s $1.5B hack and the need for stronger industry defenses2026-04
Bybit is a centralized cryptocurrency exchange that has grown from a derivatives-focused challenger into one of the world’s largest trading venues, serving tens of millions of users across spot markets, derivatives, yield products and tokenized real-world assets. It now sits at the center of three overlapping debates: how offshore exchanges enter regulated markets, whether tokenized finance can deliver more than synthetic exposure, and how institutions should assess security when a venue operates custody infrastructure at enormous scale.
That breadth can obscure what Bybit actually is. It is still fundamentally a derivatives exchange, but one trying to turn its trading engine and customer distribution into a general financial platform. The gain is a wider product relationship with each user, spanning fiat access, trading, automation and investment products. The cost is that failures no longer remain confined to one market. Custody, securities structuring, banking access, leverage controls and regulatory permissions become parts of the same institutional risk surface.
Origins, Leadership and Strategic Evolution
Bybit’s story begins in the late 2010s, when crypto derivatives were becoming a central part of the digital-asset market but remained dominated by a small group of venues with uneven reliability and risk controls. Founded in 2018, Bybit initially positioned itself as a derivatives-first exchange for traders seeking perpetual futures and related leveraged products supported by fast execution infrastructure.
That history still matters because product expansion has not replaced the original business. Spot trading, yield products and tokenized real-world assets broaden the interface, but derivatives remain the economic and cultural center of the platform. Bybit is therefore better understood as a derivatives exchange extending outward into financial distribution than as a conventional investment platform that happens to offer crypto futures.
The exchange was co-founded and is led by CEO Ben Zhou, who frequently serves as its public representative in interviews and conference appearances. Biographical profiles describe Zhou as having spent his teenage years in New Zealand, earned a degree from the University of Canterbury, worked in traditional finance and then moved into crypto. Earlier descriptions associated Bybit with Singapore, reflecting that city-state’s former importance to Asian crypto activity. More recent corporate communications come from Dubai, showing that the company’s center of gravity has shifted toward the United Arab Emirates and its developing virtual-asset framework.
This geographic movement is more than a change of address. For a global exchange, headquarters, operating entities and customer-facing licenses answer different questions. A company may employ staff in one location, serve customers through an entity in another and remain unauthorized in a third. Readers evaluating Bybit should therefore test market access entity by entity: which legal company holds the account, which regulator supervises it, which products that entity may offer and where customer assets sit.
Bybit’s growth has been rapid by the standards of crypto exchanges. Company summaries and third-party analyses have characterized it as the world’s second-largest cryptocurrency exchange by trading volume, while company messaging has described a customer base exceeding 80 million users across more than 180 countries. One market-structure breakdown placed daily derivatives volume around $22.9 billion and estimated that derivatives represented roughly 93% of total trading activity.
Those figures fluctuate with asset prices, volatility and leverage demand, so they are better read as evidence of market position than as permanent measurements. The durable conclusion is that Bybit moved from niche challenger to systemically relevant venue. At that scale, liquidation rules, wallet procedures, market outages and product disclosures can affect more than the customers immediately involved.
Bybit has also pushed into institutional and wealth-management services. In a 2025 recap, the company said Bybit Institutional’s asset inflows increased from $1.3 billion in the third quarter to $2.88 billion in the fourth. It reported that wealth-management assets under management grew from $40 million to $200 million over the same period. These are company-reported figures rather than an independent census of institutional adoption, but the comparison shows the direction of strategy: Bybit wants professional allocators to treat it as infrastructure, not merely as a retail trading application.
Institutionalization raises the standard by which the exchange should be judged. Retail convenience can be evaluated through spreads, uptime and withdrawals. Institutional infrastructure also requires dependable governance, reconciliations, reporting, settlement controls, legal clarity and operational segregation. A large balance on an exchange is not institutional simply because a fund owns it; the surrounding controls determine whether the arrangement can survive due diligence and stress.
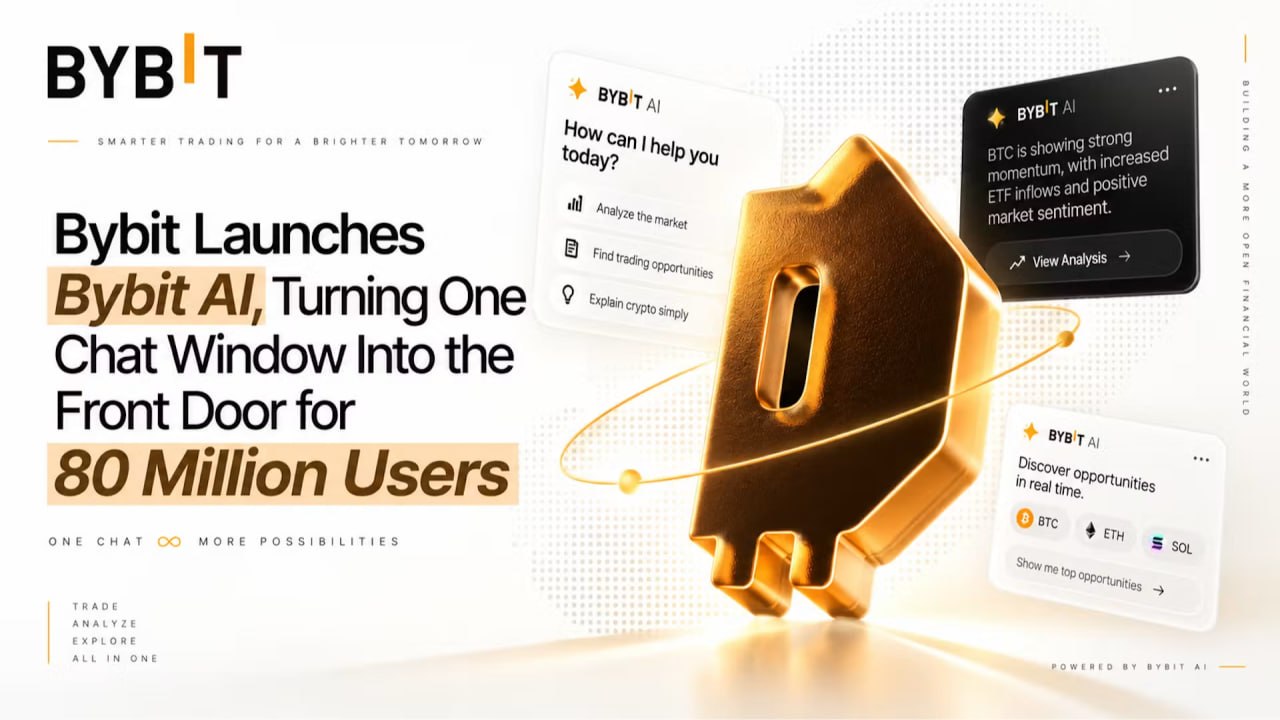
Bybit launches conversational AI assistant to unify trading and customer support in one chat interface
Core Exchange Products and Markets
Spot and Derivatives Trading
At its core, Bybit lets users trade cryptocurrencies against stablecoins or other crypto assets through centralized order books. Its public markets interface provides prices, market capitalizations, 24-hour movements, depth information and candlestick charts for major assets and a long tail of smaller tokens. This is the familiar centralized-exchange model: users deposit assets, the venue maintains an internal ledger and orders are matched within its own market infrastructure.
Derivatives define Bybit’s competitive position more clearly than spot trading. Perpetual contracts allow traders to take leveraged long or short exposure without a conventional expiry date, while other derivatives can offer dated or nonlinear payoff structures. These products attract sophisticated traders because they support hedging, capital efficiency and directional speculation. The same features make them dangerous for inexperienced users: leverage accelerates gains and losses, and liquidation can turn a temporary market move into a permanent loss.
That creates Bybit’s foundational trade-off. Deep derivatives liquidity can produce tighter execution, active price discovery and useful hedging markets, but it also aligns exchange revenue with turnover, leverage and open interest. Education and warnings may temper that incentive, but they do not remove it. A prospective user should inspect maximum leverage, maintenance-margin rules, liquidation methodology, index construction and insurance-fund arrangements before treating a headline contract as interchangeable with the same market on another venue.
The platform emphasizes matching performance, low-latency application programming interfaces and maker-taker fee schedules intended to attract liquidity providers. These are now baseline expectations for a serious derivatives venue rather than distinguishing luxuries. What separates platforms is how those systems behave during extreme volatility: whether order entry remains available, whether price indexes resist manipulation and whether liquidation engines distribute losses predictably.
From a user-lifecycle perspective, Bybit guides customers from registration and identity verification toward deposits, basic purchases and eventually more advanced products. The progression is commercially sensible because a single interface houses simple spot purchases, yield products, trading bots and leveraged contracts. It is also a form of risk segmentation. The crucial question is whether friction rises with complexity or whether an easy interface makes fundamentally different risks look deceptively similar.
Earn, Real-World Assets and Fixed-Income Vaults
Beyond trading, Bybit has invested in Earn and real-world-asset products intended to turn dormant balances into managed or structured exposure. This shifts the exchange from marketplace toward financial supermarket. A trading venue principally connects buyers and sellers; an Earn platform also selects integrations, presents return opportunities and influences how customers interpret counterparty and strategy risk.
Company recaps describe Bybit Earn as offering a range of products, including Mantle Vault, a stablecoin-denominated on-chain yield product designed around annual-percentage-rate performance. The company reported that the vault attracted $52 million in assets under management within a week of launch. Mantle’s partnership with Bybit also integrated the MNT token into uses such as fee discounts, leverage trading, real-world-asset tokenization and staking.
This kind of integration can make an exchange more useful by connecting liquidity, collateral and on-chain applications. It can also make risk harder to decompose. A user may face exposure to Bybit as custodian, a token as collateral, a vault’s smart contracts, external counterparties and the assets generating the yield. The interface unifies the experience; it does not unify the legal claims or failure modes.
Bybit has also worked with Plume on access to fixed-income vaults associated with traditional asset managers including PIMCO and CMBI, with described underlying exposures such as mortgage-backed securities and high-yield corporate bonds. In that model, stablecoins act as the subscription rail between crypto balances and portfolios rooted in conventional credit markets.
The familiar analogy is a brokerage shelf that distributes third-party funds, except tokenization can add smart-contract, custody and stablecoin layers between investor and asset. The benefit is accessibility and potentially faster movement between products. The cost is a longer chain of dependencies. Asset-manager involvement does not by itself tell a user which entity owes repayment, whether redemption is continuous, what happens after a stablecoin disruption or how insolvency claims would be ranked.
Bybit’s RWA Earn suite extends that strategy by packaging exposure to assets such as corporate credit or sovereign bonds for eligible users. Real-world-asset tokenization is often described as bringing traditional investments on-chain, but that phrase compresses several distinct structures. A token may represent direct ownership, a beneficial interest in a vehicle, a contractual claim, collateralized debt or synthetic price exposure. Two products tracking the same asset can therefore give holders very different rights.
The useful test is not whether an offering carries an RWA label. It is whether a user can identify the issuer, legal vehicle, custodian, governing jurisdiction, redemption mechanism, valuation policy, transfer restrictions and position in insolvency. Tokenization can improve distribution and settlement without improving the underlying credit. It changes the wrapper first; whether it improves the investment depends on the structure inside.
Copy Trading, Bots, Leaderboards and Campaigns
Social and automated trading features form another part of Bybit’s product stack. Its leaderboard displays performance statistics for visible traders, while Copy Trading allows designated Master Traders to have positions mirrored by followers under defined allocation and risk settings.
Copy trading turns a personal track record into a distributable strategy, closer to managed-account software than to ordinary social media. The gain is that users can observe and reproduce trading behavior without manually entering every position. The cost is that past performance can attract capital precisely when a strategy has become crowded, overfit or vulnerable to a different market regime.
Bybit documentation has described Copy Trading Bonuses that can serve as margin for copied trades and trading bots. The bonuses are non-withdrawable and subject to conditions, although profits made with them may generally be withdrawn. If a follower assigns 1,000 USDT and applies a 50 USDT bonus, for example, 950 USDT comes from the follower’s derivatives balance and 50 USDT from the promotional allocation.
That structure is best understood as subsidized risk capital rather than a cash gift. It lowers the user’s immediate funding requirement while directing activity toward selected products. The relevant comparison is not simply bonus versus no bonus, but the likely trading loss, fee burden and behavioral effect created by the promotion.
Leaderboards introduce their own selection problem. Short measurement windows reward volatility and can make a high-risk strategy look skillful before losses arrive. A reader assessing a Master Trader should examine drawdowns, position concentration, leverage, duration and performance across market regimes, not only headline returns. A result that cannot be connected to the risk taken to produce it is marketing data, not a usable investment record.
Bybit supplements these mechanics with trading competitions, airdrops and promotional campaigns. Events such as the Global Assets Trading Fest have used USDT-denominated prize pools across crypto and traditional-finance-linked markets, while token distributions encourage activity around new listings. Such campaigns can concentrate attention and liquidity, but they may also cause users to trade more frequently or aggressively than their strategy warrants.
Tokenized Equities and IPO Express
One of Bybit’s most ambitious expansions has been tokenized equities, including an IPO Express concept described in company and social-media material as enabling subscriptions with stablecoins for tokenized exposure connected to companies approaching public listings. The stated workflow allowed users to subscribe with USDC, receive tokens and trade them on Bybit after listing.
The attraction is obvious. Pre-IPO equity has traditionally been restricted by access, accreditation, private-market relationships and limited liquidity. A crypto-native wrapper promises smaller denominations, stablecoin settlement and a secondary market. Yet the product only democratizes the asset if the wrapper conveys a durable and intelligible claim. Easier trading cannot compensate for uncertain backing.
The SpaceX example exposed that weakness. Reporting described exchanges as having overestimated or misunderstood allocations of underlying pre-IPO shares through xStocks, producing a shortage of equity backing contemplated on-chain allocations. Platforms including Bybit cancelled some allocations and refunded users. The broader tokenized-equity market was reported around $5.5 billion in capitalization amid the surrounding demand.
The episode reclassifies tokenized pre-IPO access. It is not merely a faster brokerage product; it is an intermediated supply chain in which the exchange, token provider, security holder and issuer may be different parties. Each link can introduce allocation, custody, disclosure and legal-enforcement risk. Stablecoin subscription makes settlement easier, but it does not manufacture scarce shares.
For users, the central question is what the token legally represents. Direct ownership, a beneficial interest, a contractual entitlement and a derivative referencing the same company are economically related but legally distinct. A refund after an allocation failure limits immediate loss, yet it does not establish that the original structure delivered the ownership users may have inferred.
For Bybit, tokenized equities offer a route from crypto trading into mainstream capital-market exposure. They also invite capital-markets scrutiny. The more an exchange resembles a global broker, the less persuasive it becomes to treat every product as an extension of ordinary crypto spot trading. If tokenized securities become durable products, disclosure quality and enforceable holder rights will matter more than novelty or round-the-clock availability.
AI Subaccounts and Algorithmic Trading
Bybit has also moved into AI-assisted trading infrastructure. Its AI Subaccounts were designed to separate AI-agent activity from a user’s main balances while preserving monitoring and risk controls. Official descriptions presented them as isolated environments in which an agent could trade through an application programming interface without receiving unrestricted access to the entire account.
Administrators could monitor activity and define parameters around funds, leverage, withdrawal permissions and trading scope. The architecture applies an old security principle to a new interface: an automated agent should receive only the authority it needs. Segregation cannot make a trading model intelligent, but it can limit the damage caused by a defective strategy, compromised credential or misconfigured instruction.
Bybit paired this infrastructure with education and incentives, including a 30,000 USDT prize pool for qualifying identity-verified users who created an AI Subaccount or completed an eligible AI-agent trade. Promotions can accelerate experimentation, but they also complicate the language of responsible adoption. Rewarding the first use of an automated system encourages participation before long-term performance or operational reliability is known.
The correct test for an AI trading tool is not whether it can converse fluently or place an order. Users should ask what data it sees, what actions it can take, how permissions are revoked, how losses are bounded and whether every instruction and execution can be reconstructed afterward. In finance, auditability is often more valuable than apparent intelligence.
Readers clicked the Bybit hack obsessively not for the exploit mechanics but for the accountability chain: who drained the funds, who laundered them, who North Korea is, and whether anyone got caught — making the $1.5B Lazarus heist a proxy story about whether crypto's security theater can ever produce real consequences.
Regulation, Licensing and Geography
The UAE and Europe
Bybit’s regulatory posture combines a global platform with region-specific entities. Public materials have emphasized authorization in the United Arab Emirates, including a Securities and Commodities Authority Virtual Asset Platform Operator License obtained in October 2025. The license was described as supporting trading, custody and fiat services across the UAE.
An onshore license is meaningful because it places defined activities within a regulator’s perimeter. It is not a universal approval of every Bybit product or global operation. The practical question remains which services fall under the licensed entity and what protections attach to a particular account.
In Europe, Bybit pursued compliance under the Markets in Crypto-Assets Regulation through a Vienna-based operation, creating Bybit EU as a regulated crypto-asset service provider for applicable European Economic Area markets. The European arm partnered with ClearBank Europe for fiat-account safeguarding and movement between banking rails and digital-asset services.
This structure potentially gives European customers a clearer division between safeguarded fiat and exchange activity. It also illustrates why the Bybit brand should not be treated as one legal box. A European account may have different products, disclosures, counterparties and complaint routes from a global account. Harmonized branding does not imply harmonized protection.
MiCA provides a crypto-asset framework, but it does not automatically convert every securities-like or derivatives product into an authorized offering. As Bybit expands from crypto into instruments associated with equities, credit and foreign exchange, the relevant perimeter becomes more complex. The strategic benefit is access to a wider financial market; the corresponding cost is that several licensing regimes may apply to what looks like one application.
Global Footprint and Restricted Jurisdictions
Bybit does not serve every market. Its help materials have identified excluded jurisdictions including the United States, mainland China and Hong Kong. Restrictions reflect different combinations of licensing requirements, local prohibitions and product rules. They also demonstrate that global user counts and country counts should not be confused with universal availability.
Singapore illustrates the distinction. Earlier descriptions associated Bybit with the city-state, but the Monetary Authority of Singapore said Bybit Fintech Ltd. had never been licensed there to provide regulated financial services. MAS subsequently placed Bybit on its Investor Alert List, a register used for entities that may be mistakenly perceived as licensed or regulated or whose investment offers may create that impression.
Placement on the list did not by itself establish a violation of Singapore law. It did establish that users should not infer authorization from corporate history, brand visibility or former headquarters descriptions. Bybit responded that it did not serve Singapore customers and used contractual restrictions and internet-protocol blocking, while seeking clarification from MAS.
The episode captures a recurring problem for borderless exchanges. A website may be visible globally even when service is contractually unavailable, and users may use technical workarounds that do not change the governing law. The observable test is local authorization, not whether the interface can be reached. A user bypassing geographic controls may also bypass the protections and remedies they assumed would apply.
KYC, Onboarding and Compliance Controls
Within supported markets, Bybit has progressively tightened identity verification. Its guides describe identity checks as necessary for fiat options, higher withdrawal limits and access to selected campaigns or products. The process generally involves personal information, government-issued identification and a selfie, followed by automated or manual review.
Know-your-customer controls are often treated as a binary sign of legitimacy, but their value depends on execution. Identity checks can reduce account abuse and support sanctions or anti-money-laundering screening. They do not prove solvency, prevent custody theft or guarantee that every product is suitable. Compliance controls address particular risks, not the entire platform.
Bybit supports crypto deposits, fiat transfers, payment processors and peer-to-peer purchases. One-Click Buy combines multiple rails in a simplified interface, while the P2P market connects buyers and sellers under exchange rules and escrow arrangements. These options expand access, particularly where direct banking links are limited, but each introduces a different counterparty and dispute path.
A bank transfer, card purchase, internal balance conversion and P2P trade may look like adjacent buttons while creating different fees, execution prices and reversal risks. Ease of use is therefore a presentation feature, not a substitute for understanding the payment rail underneath.
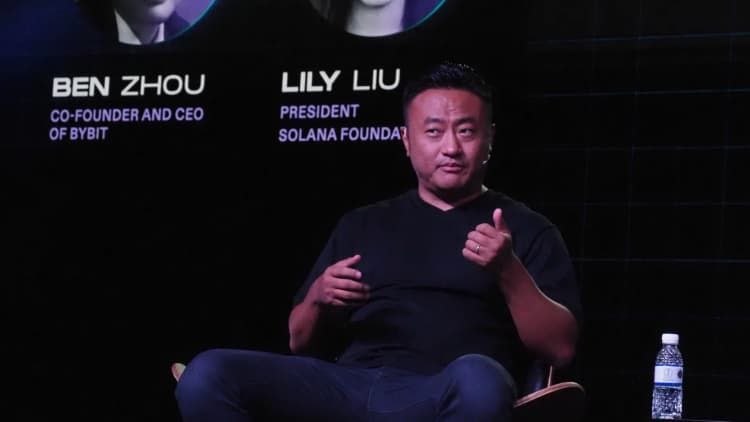
Bybit plans European super-app offering stocks and derivatives as CEO Ben Zhou confirms the crypto exchange is pursuing a MiFID license in Austria
Security, Hacks and Risk Management
Custody and Proof of Reserves
Security is central to evaluating a centralized exchange because customers transfer control of their assets to the venue. Bybit has emphasized cold storage, multisignature approvals and monitoring, while third-party observers have cited Merkle-tree proof-of-reserves information and security-platform ratings.
Proof of reserves addresses a specific question: whether observable assets correspond to included customer liabilities at the time and within the scope of an attestation. A Merkle tree can let an individual verify that an account balance was included without exposing every customer’s balance. On-chain reserve addresses can then provide evidence of assets controlled by the exchange.
That is valuable, but incomplete. A proof may omit liabilities outside its scope, fail to capture off-chain obligations or say little about corporate claims and operational controls. It is closer to a balance-sheet snapshot than a full audit, and it does not demonstrate that the assets will remain secure after publication.
The distinction between solvency and security is essential. A venue can hold enough assets and still lose them. It can also maintain technically secure wallets while carrying undisclosed liabilities. Users should ask what the proof covers, when it was produced, how liabilities are represented and whether an independent party tested the process.
The 2025 Ethereum Cold-Wallet Theft
In February 2025, Bybit suffered one of the largest cryptocurrency thefts on record through a workflow involving an Ethereum multisignature cold wallet. The unauthorized activity was detected on February 21 during what was supposed to be a routine transfer from a cold wallet to a hot wallet used for exchange liquidity.
Post-incident accounts described attackers manipulating the approval process so authorized signers believed they were confirming a legitimate internal transfer while granting control to attacker-controlled addresses. Estimated losses ranged from $1.4 billion to $1.5 billion and included ETH, staked ETH and other ERC-20 assets associated with the wallet environment.
Investigators and public reporting attributed the operation to actors linked to North Korea’s Lazarus Group, with the Federal Bureau of Investigation connecting it to the broader TraderTraitor cluster. Attribution helps explain the sophistication and likely laundering strategy, but it does not reduce the operational lesson: multisignature security fails if signers cannot reliably verify what they are authorizing.
The event was reported as an exchange-wallet theft rather than a confirmed mass breach of customer databases or individual retail wallets. Public accounts focused on custodial assets, not confirmed exposure of customer personally identifiable information or unencrypted retail keys. That distinction bounds what the incident establishes, but it should not be mistaken for a minor event. Customers were exposed to the exchange’s custody failure because the exchange controlled pooled assets on their behalf.
Bybit launched a LazarusBounty program offering a 10% reward connected to recovery of stolen funds. Recovery incentives can help identify laundering routes or encourage intermediaries to freeze assets, but they operate after control has already failed. Prevention depends on transaction verification, secure administrative interfaces, constrained permissions and procedures that remain robust when operators face convincing deception.
The attack exposed the limits of blind signing. Multiple approvals provide protection only when approvers independently understand the transaction and validate its destination and effects through trustworthy channels. If every signer relies on the same compromised interface, additional signatures can reproduce the same error rather than provide independent assurance.
The incident also complicates the use of security ratings. A high score can describe controls visible to the rating provider, but it cannot certify immunity from targeted compromise. The breach does not make every prior control meaningless; it establishes that the evaluated system still contained a catastrophic path to loss.
Lessons for Users and Institutions
Centralized exchanges concentrate liquidity for the same reason they concentrate attack incentives. Pooling assets improves trading efficiency, collateral movement and settlement, but it creates a large prize protected by operational processes that adversaries can study. The result is not that centralized custody is always unacceptable. It is that convenience and concentration must be priced together.
For individual users, self-custody can reduce exposure to exchange failure but adds key-management risk. Keeping assets on an exchange simplifies trading and recovery but transfers control to the venue. The sensible balance depends on purpose: capital needed for active trading has a stronger reason to remain on-platform than long-term holdings with no immediate use.
Account protections such as multifactor authentication, withdrawal-address whitelists and segregated subaccounts can reduce account-level compromise. They do not defend against every institutional-wallet failure. Users should therefore distinguish controls they can operate from risks only the exchange can manage.
Institutions face a broader diligence problem. They need to evaluate wallet architecture, transaction authorization, segregation, incident response, reporting, legal entities and the ability to reconcile balances across systems. Insurance, if present, must be tested for limits and exclusions rather than treated as a generic promise of reimbursement.
- 01Lazarus Group identity and laundering↗
ZachXBT's on-chain forensics tracing 920 addresses, Tornado Cash deposits, and THORChain's $5.5B laundering volume gave readers a real-time criminal investigation they could follow wallet by wallet.
- 02$1.5B hack root cause↗
The DELEGATECALL Safe proxy rewrite — exploiting a skipped hardware wallet verification — was a specific, teachable failure that exposed industry-wide multisig complacency.
- 03CEO Ben Zhou crisis response↗
Zhou's live stream, LazarusBounty site launch, and public fund-tracing updates made readers track whether an exchange CEO could actually lead a credible recovery rather than disappear.
- 04North Korea state-actor escalation
North Korea becoming the third-largest Bitcoin holder after converting stolen ETH reframed the hack as geopolitical, not just criminal — readers wanted to know what governments would do.
- 05Market panic and withdrawal cascade
The $4.3B market exodus and 10,000 BTC long liquidation showed readers how a single custodial failure could trigger systemic deleveraging across the entire market.
- 06Proof-of-reserves transparency failure
The hack arriving after a 'half-baked' proof of reserves crystallized reader skepticism about whether exchange solvency attestations mean anything under stress.
User Experience and Fiat Access
Registration begins with an email address or mobile number, followed by identity verification where required. Verified users can deposit crypto from external wallets or use regional fiat options such as bank transfers, cards and third-party payment providers. Fiat balances may enter a Funding Account before being moved into spot, derivatives or Earn products.
The integrated ledger makes movement between products fast. That is operationally useful, but it can blur boundaries between cash-like balances, collateral and invested assets. A user should know whether a balance is immediately withdrawable, committed to a strategy, pledged as margin or exposed to a redemption delay.
One-Click Buy reduces the complexity of order books by routing users through supported payment methods. The trade-off is less visibility into execution. Simplicity can conceal processor spreads, card charges or differences between an internal conversion and an open-market order.
The P2P portal uses Bybit as an escrow and reputation layer while users complete local fiat payments directly with one another. This can provide access where conventional ramps are weak, but disputes may involve evidence from payment systems outside Bybit’s control. Users should verify counterparties, payment names and release conditions rather than treating platform escrow as protection against every form of fraud.
Educational resources and beginner products can help users navigate this range, but product labels are not risk classifications. A flexible savings product, structured vault and leveraged perpetual may occupy the same application while depending on completely different mechanisms. The interface should be read as navigation, not as a promise that adjacent products are equally safe.
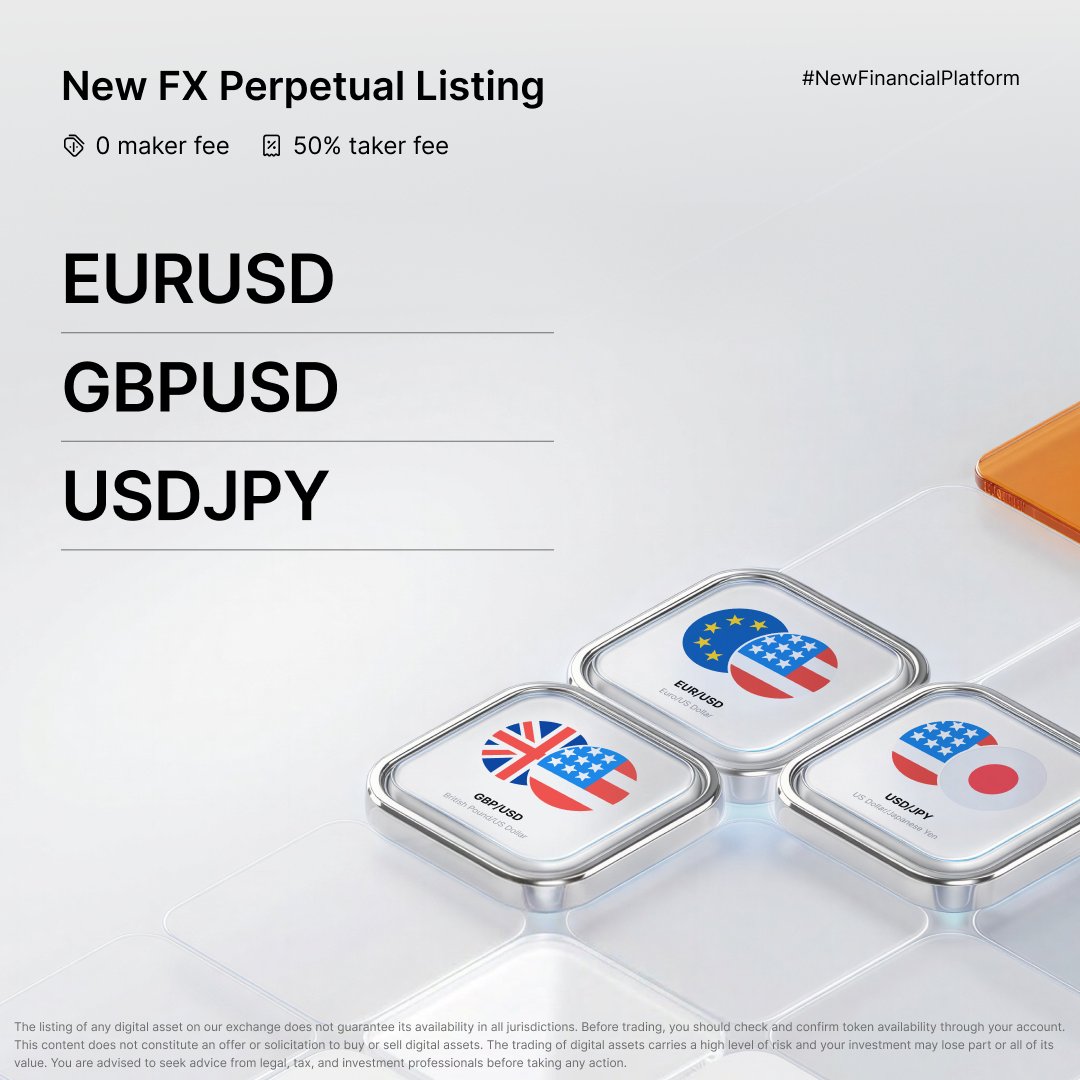
Bybit launches USDT-settled FX perpetual contracts for EUR/USD, GBP/USD, USD/JPY
Competitive Positioning
Bybit is most often compared with Binance and Coinbase, though each reflects a different exchange model. Binance represents scale and product breadth accompanied by complicated global regulation. Coinbase represents a publicly listed, U.S.-regulated gateway with a comparatively conservative product posture. Bybit sits between them: derivatives-heavy and willing to experiment, while building regulated regional operations in the UAE and Europe.
That middle position can be an advantage. Bybit can combine active crypto markets with tokenized assets, automated trading and regional banking infrastructure. It can also become strategically unstable if the platform promises offshore-style product breadth and onshore-style regulatory assurance at the same time. Those models impose different constraints.
Hyperliquid adds a different kind of competition because it moves derivatives activity on-chain. Ben Zhou has described the venue as more partner than direct competitor and suggested traders may use both platforms for different purposes. The larger point is that centralized and decentralized exchanges are converging. Centralized venues integrate on-chain products, while decentralized systems compete on trading quality and professional interfaces.
Users should compare the custody model as much as the product list. A centralized venue can offer efficient execution and account recovery but requires trust in the operator. An on-chain venue can make positions and collateral more observable while adding smart-contract, oracle and wallet risks. Neither category eliminates intermediation; each relocates it.
- 2024-07exploit
WazirX hack linked; funds routed through Bybit
$1.5B Lazarus Group hack via Safe DELEGATECALL exploit
- 2025-02milestone
$4.3B market exodus and 10,000 BTC long liquidation
- 2025-02milestone
Ben Zhou launches LazarusBounty transparency site
- 2025-03exploit
Lazarus fully launders 500,000 ETH via THORChain into BTC
- 2025-03milestone
North Korea becomes third-largest Bitcoin holder
- 2025-04governance
Bybit winds down NFT and IDO platforms post-hack
- 2025-06milestone
Bybit ceases support for zkSync Lite network
Tokenization and the Race for RWA Market Share
Bybit’s combination of RWA products and derivatives gives it a distinctive place in the tokenization race. It can distribute conventional-asset exposure to a large trading audience and potentially allow those exposures to interact with collateral, automation and secondary markets.
The promise is not simply that traditional assets become available around the clock. It is that settlement, denomination and programmability may change how portfolios are assembled. The danger is that liquidity in a token can be mistaken for liquidity in its backing asset. A wrapper trading continuously cannot guarantee continuous creation or redemption when the underlying market is closed, restricted or illiquid.
Fixed-income products create another mismatch. A token may move instantly while mortgages, corporate bonds or private credit instruments settle slowly and trade sporadically. The token’s apparent liquidity therefore depends on reserves, market makers, redemption terms and valuation procedures. In stressed markets, those mechanisms matter more than the blockchain transfer speed.
Bybit’s distribution can accelerate adoption, but scale magnifies structural errors. If legal rights are clear and redemptions work, the exchange could become a meaningful gateway between stablecoins and traditional assets. If wrappers outrun their backing or permissions, the same distribution will spread confusion quickly.
The February 2025 hack exploited a malicious DELEGATECALL that rewrote Safe multisig proxy logic after bypassing hardware wallet verification, draining $1.5B from a single cold-wallet operation.
- CentralizationHigh
Bybit's reliance on a small set of signers for its ETH cold wallet meant a single compromised signing ceremony could authorize an $1.5B transfer with no circuit breaker.
Bybit appears on the MAS investor alert list, restricts numerous jurisdictions, and its CEO acknowledged Chinese users need VPNs to access the exchange, signaling persistent licensing and compliance exposure.
The breach implicated Safe's signing infrastructure and cascaded into mETH Protocol and multiple DeFi platforms, revealing that Bybit's security perimeter extended through third-party wallet tooling it did not control.
- LiquidityMedium
The hack triggered $4.3B in panic withdrawals per Glassnode; Bybit survived but only through rapid emergency liquidity measures, demonstrating thin margin for error during bank-run scenarios.
- MarketMedium
Bybit's open interest wiped 10,000 BTC in longs within two hours of the incident becoming public, showing how custodial crises instantly transmit into derivatives market dislocations.
Risks, Criticisms and User Due Diligence
Bybit’s primary risks are not isolated; they reinforce one another. Derivatives create leverage and liquidation exposure. RWA products add issuers, custodians and legal vehicles. Fiat ramps add banking partners and payment processors. Automation adds delegated permissions. Centralized custody places the resulting balances inside a security perimeter that has already experienced a catastrophic breach.
Regulatory fragmentation compounds the problem. A license in one market does not authorize service in another, and the availability of a website does not create local protection. Users should identify the account entity and product permission before relying on the reputation of the global brand.
Product due diligence should begin with ownership. For any tokenized investment, a user should be able to explain what legal claim the token conveys, who owes the obligation, where backing is held, how it is valued and how redemption works. If those answers depend only on a product name or interface label, the structure is not yet clear enough to assess.
Trading due diligence should focus on loss mechanics. Leverage limits, margin rules, liquidation prices and promotional incentives matter more than leaderboard returns. A reward that encourages additional turnover can be economically negative even when the user receives it.
Custody due diligence should separate proof of assets, proof of liabilities and proof of control. Reserve attestations can illuminate the first two within a defined scope. Wallet governance, signer verification and operational security determine the third. The 2025 theft showed that possession of adequate assets before an attack does not ensure possession afterward.
Outlook
Bybit’s trajectory depends on regulatory integration, tokenization maturity and operational security. Its regulated footholds in the UAE and Europe give it a stronger institutional foundation than an entirely offshore model, while restrictions and warnings elsewhere show the limits of brand-level claims about global availability.
Its product direction is equally clear. Bybit wants to connect crypto derivatives, spot markets, stablecoins, real-world assets and automated trading inside one financial interface. That is less an exchange expansion than an attempt to become a cross-asset operating layer.
The gain is convenience and capital efficiency: users can fund, trade, hedge and invest without repeatedly leaving the platform. The cost is concentrated dependency. A failure in custody, legal structuring, market controls or banking access can affect several parts of the relationship at once.
The decisive tests are observable. Regulated entities must keep permissions aligned with the products they distribute. Tokenized assets must maintain intelligible legal claims and dependable redemptions. Automated systems must remain constrained and auditable. Custody procedures must show that human approvals independently verify transaction effects rather than reproduce a compromised interface.
If Bybit can satisfy those tests, its derivatives liquidity and product distribution could support a durable tokenized-finance platform. If legal rights, operational controls or backing remain less mature than the interface, the platform’s breadth will amplify risk faster than it creates financial infrastructure.
Latest Bybit news
Bybit launches conversational AI assistant to unify trading and customer support in one chat interfaceBybit plans European super-app offering stocks and derivatives as CEO Ben Zhou confirms the crypto exchange is pursuing a MiFID license in AustriaBybit launches USDT-settled FX perpetual contracts for EUR/USD, GBP/USD, USD/JPYSources
20 records from 13 domains
cryptonews.net
bybit.com
allamericanspeakers.com
mas.gov.sg
huntress.com
facebook.com
x.com
clear.bank
prnewswire.com
binance.com
instagram.com
fortune.com
announcements.bybit.com
Community notes
Spot something off or out of date? Drop a note. Editors review topic notes daily and roll accepted fixes into the explainer — contributors are recognized in the monthly $SQUID drop.
Loading notes…
Help improve this topic
Have a story or tip about this topic? Submit it. See something missing? Leave a note. Editors review daily; accepted submissions and fixes count toward the monthly $SQUID drop.