
The UK is replacing its narrow crypto registration system with full regulation. Its prospects now turn on authorisation, stablecoin policy, retail access, enforcement, and whether regulated products can compete with overseas markets.
+45 sources across the wider coverage universe
 Coinbase teams up with US Secret Service and UK NCA to freeze $12M stolen via phishing, identifying over 20,000 victims as blockchain speed outpaces traditional finance response times2026-04
 UK finalises 2026 crypto rules with DeFi carve-out, exempting truly decentralised protocols while requiring FCA oversight for projects with identifiable controlling entities2026-04
 Operation Atlantic freezes $12M, identifies 20,000+ victims in US-UK-Canada approval phishing crackdown2026-04
 FCA opens consultation on UK crypto regime covering stablecoins, exchanges, and staking ahead of 2027 launch2026-04
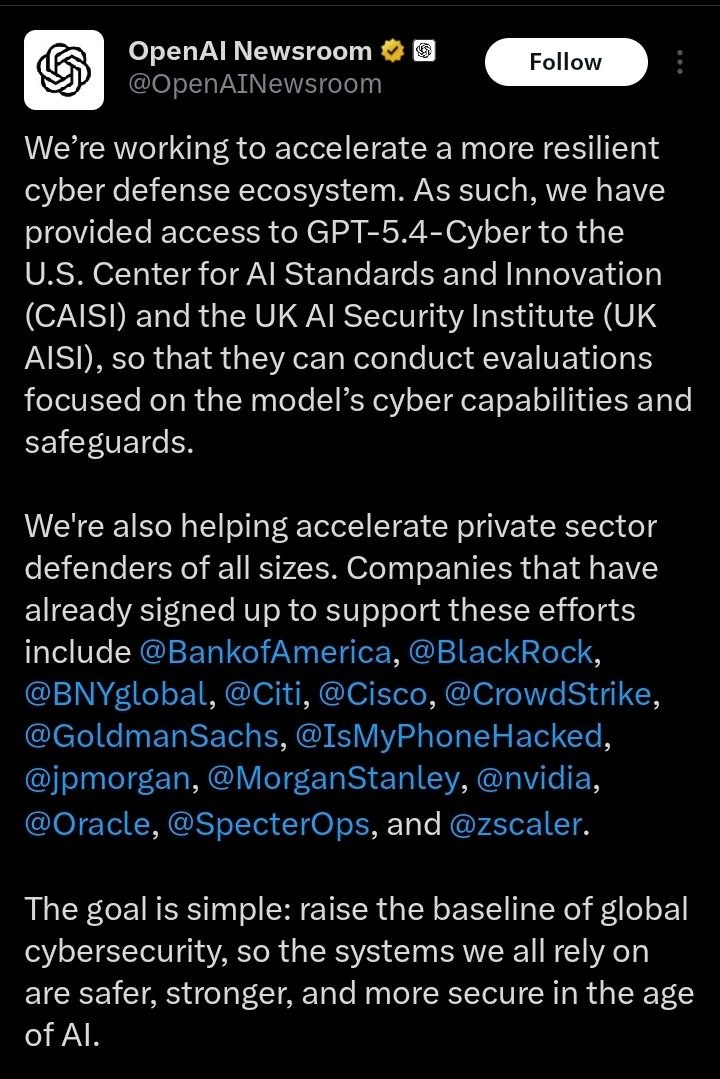 OpenAI expands cybersecurity push with GPT-5.4-Cyber access for US and UK agencies, partnering with banks and tech giants to strengthen global AI defense systems2026-04
 Consensys' Bill Hughes calls UK FCA crypto proposal a 'mother, may I' regime broader than MiCA or US2026-04
The United Kingdom has emerged as one of the most consequential battlegrounds for crypto regulation outside the United States, balancing ambitions to become a global digital-asset hub against firm consumer-protection instincts. The important shift is categorical: crypto is moving from the edge of the existing financial system into a purpose-built regulatory perimeter, with the costs and protections that transition entails.
The Legislative Framework Taking Shape
For most of the 2020s, crypto firms operating in the UK faced a patchwork of obligations rather than a coherent regime. Anti-money-laundering registration with the Financial Conduct Authority was mandatory but narrow; broader rules governing trading, custody, and issuance did not exist.
That changed materially in early 2026. The Financial Services and Markets Act 2000 (Cryptoassets) Regulations 2026 were made by Parliament on 4 February 2026, formally bringing cryptoassets within the FCA's regulatory perimeter for the first time. The regime is expected to come into force on 25 October 2027, with an authorisations gateway opening on 30 September 2026. Final conduct-of-business rules are expected to be published in late 2026.
The FCA has been consulting on multiple work-streams in parallel: stablecoin issuance and custody, prudential requirements, market abuse, admissions and disclosures, and the broader application of its handbook. The breadth of that programme matters because the UK is designing a layered financial-services regime, not merely expanding an anti-money-laundering register.
Regulated activities under the new rules will include operating a cryptoasset exchange, providing cryptoasset custody, issuing qualifying stablecoins, and arranging deals in cryptoassets. Firms already registered under the Money Laundering Regulations will need to obtain full authorisation. Registration is therefore best understood as a checkpoint rather than a permanent licence: it establishes that a firm has passed the narrower anti-money-laundering gateway, not that it already satisfies the forthcoming conduct and prudential regime.
That distinction is visible in a new market entrant. Robinhood secures UK crypto registration under FCA’s AML regime ahead of 2027 overhaul — the FCA register supplies the relevant regulatory record. The gain is an operating foothold before the transition; the cost is that registration does not remove the need to clear the more demanding authorisation process created for 2027.
UK FCA considers exempting tokenized gold from fund rules as regulators seek to unlock bullion reserves for collateral and strengthen London’s global gold market position
The FCA's Evolving Stance on Retail Exposure
The FCA spent much of 2021–2024 restricting retail access to crypto, banning the promotion of high-risk tokens to ordinary consumers in 2023 and limiting the range of products available on UK platforms. That posture has begun to soften as the regulator attempts to balance consumer protection with competitiveness.
The clearest signal came in June 2026, when the FCA proposed allowing authorised investment funds to allocate up to 10% of scheme property to crypto exchange-traded notes. The proposal covered UCITS schemes and most non-UCITS retail schemes. Its consultation timetable contemplated possible inclusion in the FCA Handbook during the second half of 2026.
The 10% ceiling is calibrated deliberately: exceeding it would reclassify the fund as a mass-market speculative investment, triggering stricter distribution rules. Qualified investor schemes, which are limited to professional and sophisticated clients, face no cap under the proposal.
This is controlled exposure rather than retail liberalisation. The proposal would give conventional funds a regulated channel into crypto-linked instruments while limiting the extent to which a diversified retail portfolio can become a directional crypto bet. The benefit is access through familiar fund governance; the price is a ceiling that keeps crypto structurally subordinate inside ordinary schemes.
Professional markets show the other side of that segmentation. Coinbase brings 170+ derivatives contracts to UK professional investors, with perpetuals offering up to 50x leverage — Coinbase's announcement describes the professional-investor expansion. The contract count indicates breadth, while the leverage limit explains why the distinction between professional and retail access matters: a large product shelf can deepen institutional participation, but leverage magnifies liquidation risk as efficiently as it magnifies exposure.
The UK's direction also narrows part of the gap with other large markets. Bitcoin exchange-traded products have traded on regulated European exchanges since 2019, while the United States approved spot Bitcoin ETFs in January 2024. For asset managers that had kept crypto exposure out of their UK retail vehicles, the FCA proposal opens a viable route without treating crypto as an unrestricted portfolio allocation.
UK readers click hardest on stories where crypto's legal legitimacy hangs in the balance — property rights, banking access, and regulatory gatekeeping — revealing that the dominant anxiety is not volatility or hacks but whether the UK will let crypto exist as a normal financial instrument at all.
Stablecoins: A Policy Fault Line
Nowhere is the tension in UK crypto policy more visible than in the stablecoin debate, where the FCA, the Bank of England, and the House of Lords have adopted noticeably different positions.
The FCA has identified stablecoin payments as a priority for 2026 and is building a licensing regime for qualifying stablecoins: cryptoassets referencing a single fiat currency, issued from within the UK, and backed by fiat or high-quality liquid assets. The FCA says the regime will require authorisation and address reserves and operational resilience.
The Bank of England, however, has proposed stricter constraints on the retail side: a £20,000 cap on individual stablecoin holdings and a requirement that 40% of reserve assets be held at the central bank. Proponents argue that these safeguards protect financial stability and limit run risk in a stress scenario.
The House of Lords has pushed back, calling on the Bank of England in mid-2026 to drop both the holding cap and the 40% central-bank backing requirement. Its concern is that tight constraints could push stablecoin issuers and their deposits offshore, weakening the attempt to build a domestic digital-payments market.
This is not simply a dispute between enthusiasm and caution. It is a disagreement about what stablecoins actually are. Treating them principally as payment infrastructure favours usability, competitive issuance, and broad circulation. Treating them as potential sources of deposit flight favours reserve control and holding limits. The first approach accepts more private-sector risk in exchange for adoption; the second reduces systemic exposure but may leave a formally safe market with little commercial relevance.
The test is observable: issuers must decide whether to seek UK authorisation, users must be willing to hold and spend the products, and reserves must remain credible under stress. If the framework attracts issuance while preserving redemption confidence, the UK can support a regulated sterling stablecoin market. If constraints make issuance uneconomic or use impractical, activity can migrate even though the domestic rules look robust on paper.
UK House of Lords passes amendment requiring a national digital asset strategy within 12 months

Tokenisation Beyond Crypto Trading
The regulatory perimeter is also beginning to meet London's established financial markets. UK regulator drafts tokenised gold framework to bolster London’s role in global bullion trading — the Financial Times report describes the framework under development. This reclassifies tokenisation from a crypto-sector product story into market-infrastructure policy: the underlying question is whether conventional assets can gain programmable settlement and distribution without losing the legal certainty expected in wholesale finance.
Gold is an instructive test because tokenisation does not remove the old obligations. The digital representation still depends on custody, title, redemption, market integrity, and confidence that the token maps reliably to the underlying asset. The gain is potentially more flexible distribution and settlement; the cost is another technical and legal layer through which ownership must be proved.
The framework's value will therefore depend less on the word “tokenised” than on the answers to practical questions. Market participants should be able to determine who holds the bullion, what claim the token grants, how redemption works, which records prevail during a dispute, and what happens if an intermediary fails. Those are the same institutional questions that separate durable financial infrastructure from a tradable wrapper.
- 01Property rights & legal recognition
The Parliament bill classifying crypto as personal property was the single highest-clicked story, signalling readers see legal status as the foundational unresolved question for UK holders.
- 02Banking access friction
JPMorgan's ban, Gemini's TRUST-registration wall, and the FCA retail borrowing ban collectively show readers tracking whether mainstream financial rails will open or close to crypto.
- 03Fintech bridging mainstream spend
MetaMask Mastercard and Revolut X launches drew heavy clicks as concrete proof points that crypto-to-fiat spending is arriving in the UK now, not hypothetically.
- 04Tokenisation & CBDC infrastructure
Barclays, the Regulated Liability Network, Monument Bank, and the £14tn opportunity framing show readers tracking whether the UK will lead or lag on institutional digital money rails.
- 05Regulatory framework build-out
FCA rules on borrowing, CARF reporting mandates, the 2025 framework announcement, and the DeFi tax consultation pulled readers watching how tightly the UK will govern the space.
- 06Crypto crime & North Korea exposure
Lazarus Group hacks on UK startups, NK operatives in UK blockchain projects, the Tether-Russia sanctions probe, and the Evolved Apes rug pull charges signal readers tracking criminal exposure in the UK ecosystem specifically.
Consumer Access: Banks, Exchanges, and Advocacy
Regulation is only part of the story. Many UK crypto users face a more immediate obstacle: banks blocking or delaying transfers to crypto exchanges.
Data cited by Stand With Crypto UK, a campaign backed by Coinbase, says that 40% of attempted bank-to-exchange crypto transactions face delays or blocks. The organisation, which claims more than 286,000 registered advocates, has announced plans to mobilise supporters to file formal complaints with the FCA and their banks, turning scattered individual frustrations into coordinated regulatory pressure.
The banking-access issue is not unique to the UK, but it is particularly acute in a market where payment and conduct regulators have historically given banks significant discretion to refuse transactions they deem high-risk. Critics argue that blanket restrictions amount to de-banking without individual assessment; banks point to fraud and scam exposure.
Both sides identify a real cost. Permissive transfers give lawful users control over their money but can accelerate irreversible fraud. Broad blocking policies reduce some losses but also make access to a lawful asset class depend on a customer's bank. A useful test is whether institutions disclose intelligible rules, distinguish between counterparties, provide an appeal route, and produce evidence that restrictions correspond to risk rather than to crypto as a category.
Revolut occupies an unusual position in this debate because it is simultaneously a licensed UK bank and a large retail crypto trading platform. That creates a commercial interest in smoother crypto-to-fiat flows that most incumbent banks lack, while also leaving it responsible for the fraud controls expected of a bank.
Liquida goes live on Arbitrum testnet, targets tokenised UK gilts repo market by Q1 2027
Enforcement, Fraud, and Sports Sponsorship
The FCA has used its existing powers actively even before the new regime comes into force. In 2026, UK authorities joined Ghanaian counterparts in a cross-border blockchain investigation that recovered $15 million in crypto fraud proceeds. The case demonstrated the practical utility of on-chain traceability for law enforcement, although recovery in one investigation does not establish that most stolen crypto can be identified or returned.
On sanctions, the UK government expanded its crypto-related framework to curb Russian sanctions evasion, and major exchanges increased scrutiny of transfers involving HTX, a platform linked in the standing record to sanctioned networks. The policy trade-off is familiar: transaction monitoring can obstruct illicit flows, but its effectiveness depends on attribution, cross-border cooperation, and regulated intermediaries having enough information to act.
The FCA has also warned Premier League football clubs against signing sponsorship deals with unauthorised crypto firms. That intervention follows its 2023 promotion rules and reflects concern that a prominent sports partnership can lend an unregulated entity credibility with retail audiences.
Sports sponsorship belongs in the distribution story, not merely the advertising story. A club transfers attention and trust to a sponsor; the sponsor provides revenue but gains access to an audience that may not distinguish brand visibility from regulatory approval. The reader's test is straightforward: identify which legal entity offers the product, check whether it is authorised for the relevant activity, and do not treat a club badge as evidence of financial supervision.
Aave Labs provides a counterexample to the idea that the route is closed. Its UK subsidiary secured dual FCA licences in 2026 covering regulated crypto payments infrastructure and exchange operations. That establishes that a well-resourced crypto firm can navigate the current pathway; it does not establish that authorisation will be equally accessible to smaller businesses or that existing permissions automatically satisfy the 2027 regime.
- 2023-10regulatory
UK bans promotional NFTs and airdrops under new FCA rules
- 2024-03milestone
Regulated Liability Network tokenisation pilot completes experimental phase
- 2024-06regulatory
JPMorgan UK bans crypto transactions to customer accounts
- 2024-07regulatory
Parliament introduces bill classifying crypto as personal property
- 2024-09exploit
Lazarus Group linked to $23M hack on UK crypto startup Lykke
- 2025-01regulatory
UK unveils comprehensive crypto regulatory framework
- 2025-03launch
MetaMask card EU/UK pilot launches for Mastercard crypto spend
- 2026-01regulatory
CARF crypto tax reporting rules take effect; fines up to £300 per user
Crypto, Politics, and Influence
Crypto has become an active force in UK domestic politics, raising questions about transparency and influence that extend beyond technical regulatory debates.
Reform UK, led by Nigel Farage, received multiple large donations from crypto-connected donors in 2025–2026, including a reported £7 million tranche. The party also received a reported $6.7 million gift from a Tether-linked billionaire, with Labour MPs questioning the source. The intersection of crypto wealth and political funding has consequently become a live issue for electoral regulators.
Separately, Bitcoin Policy UK publicly criticised MicroStrategy founder Michael Saylor's investment-promotion activities in the UK as “dishonest.” The episode reflects a division within crypto advocacy between groups focused specifically on Bitcoin and those seeking broader digital-asset legitimacy.
These disputes show that crypto is no longer a niche technology conversation in Westminster. It is simultaneously an industry seeking rules, a source of political funding, a lobbying constituency, and a subject of partisan conflict. The relevant standard is not whether money originated in crypto, but whether donation sources, recipients, and applicable disclosures can be scrutinised under the same rules applied to other political funding.
- RegulatoryHigh
The UK is simultaneously building a comprehensive framework, imposing CARF tax reporting from January 2026, and the FCA is actively restricting retail leverage and promotional activity — creating a dense, fast-changing compliance surface.
- CentralizationMedium
FCA TRUST registration requirements have already forced Gemini to cut off UK customers from transferring to non-registered counterparties including Binance, concentrating flow through a narrow approved set.
- MarketMedium
A potential UK government sell-off of its seized £5B Bitcoin trove to address fiscal gaps represents a discrete, government-controlled overhang on BTC price.
- Smart-contract / ExploitMedium
North Korea's Lazarus Group executed a $23M hack on UK-based Lykke and infiltrated UK blockchain projects via developer cover, showing the UK startup scene is an active target.
- LiquidityMedium
The FCA's proposed ban on retail investors borrowing to buy crypto, combined with banking restrictions, narrows the capital channels available to UK retail participants.
- Sanctions / AMLHigh
Joint US-UK investigation into $20B of Tether flowing through sanctioned Russian exchange Garantex underscores that UK regulators are treating stablecoin sanctions exposure as a priority enforcement area.
UK vs. the World
The UK's approach sits in an increasingly crowded field. The European Union's Markets in Crypto-Assets framework came into full effect in late 2024, giving firms a single passport across 27 member states—an advantage the UK surrendered at Brexit. The United States moved aggressively in 2025–2026 to pass federal crypto legislation and approve a wider range of crypto investment products under an administration explicitly favourable to the industry.
The UK's response has been to emphasise regulatory quality over speed: a principles-based regime, coordination between the FCA and Treasury, and an ambition to become a reference point for responsible digital-asset regulation. The benefit is the prospect of rules integrated with an established financial-services system. The cost is time: firms can choose Dublin, Luxembourg, New York, or another jurisdiction while the UK completes its framework.
That competition cannot be judged from consultation papers alone. The useful measures are how long authorisation takes, whether firms can obtain banking services, whether stablecoin economics remain viable, whether consumer protections work in practice, and whether regulated products attract meaningful activity.
Outlook
The UK is entering a decisive implementation period. The authorisations gateway opens in September 2026, and the full regime is expected in late 2027, giving firms time to build compliance systems after the regulations were made. Signals of greater openness—including the FCA's proposed 10% crypto-ETN allocation and completed licensing cases—sit beside tougher prudential, promotional, and market-integrity expectations.
The deeper change is that access and control are being allocated by market segment. Retail funds may receive bounded exposure, professional investors can reach leveraged derivatives, registered businesses must prepare for fuller authorisation, and tokenisation is moving into established markets such as bullion. That structure can support innovation without treating every user or product as equivalent, but it also raises the cost of entry and makes regulatory classification commercially decisive.
If the FCA converts its consultations into workable rules, the Bank of England finds a stablecoin design that issuers and users can tolerate, banks replace indiscriminate blocking with risk-based controls, and authorisation remains navigable, London can become a credible centre for regulated digital assets. If any of those links fails, formal clarity may arrive without the market activity the framework was built to govern.
Latest UK news
UK FCA considers exempting tokenized gold from fund rules as regulators seek to unlock bullion reserves for collateral and strengthen London’s global gold market positionUK House of Lords passes amendment requiring a national digital asset strategy within 12 monthsLiquida goes live on Arbitrum testnet, targets tokenised UK gilts repo market by Q1 2027 Smarter Web Company plans UK-first Bitcoin-linked preferred shares on LSE, targeting £15-25m raise
Sources
2 records from 2 domains
Community notes
Spot something off or out of date? Drop a note. Editors review topic notes daily and roll accepted fixes into the explainer — contributors are recognized in the monthly $SQUID drop.
Loading notes…
Help improve this topic
Have a story or tip about this topic? Submit it. See something missing? Leave a note. Editors review daily; accepted submissions and fixes count toward the monthly $SQUID drop.